
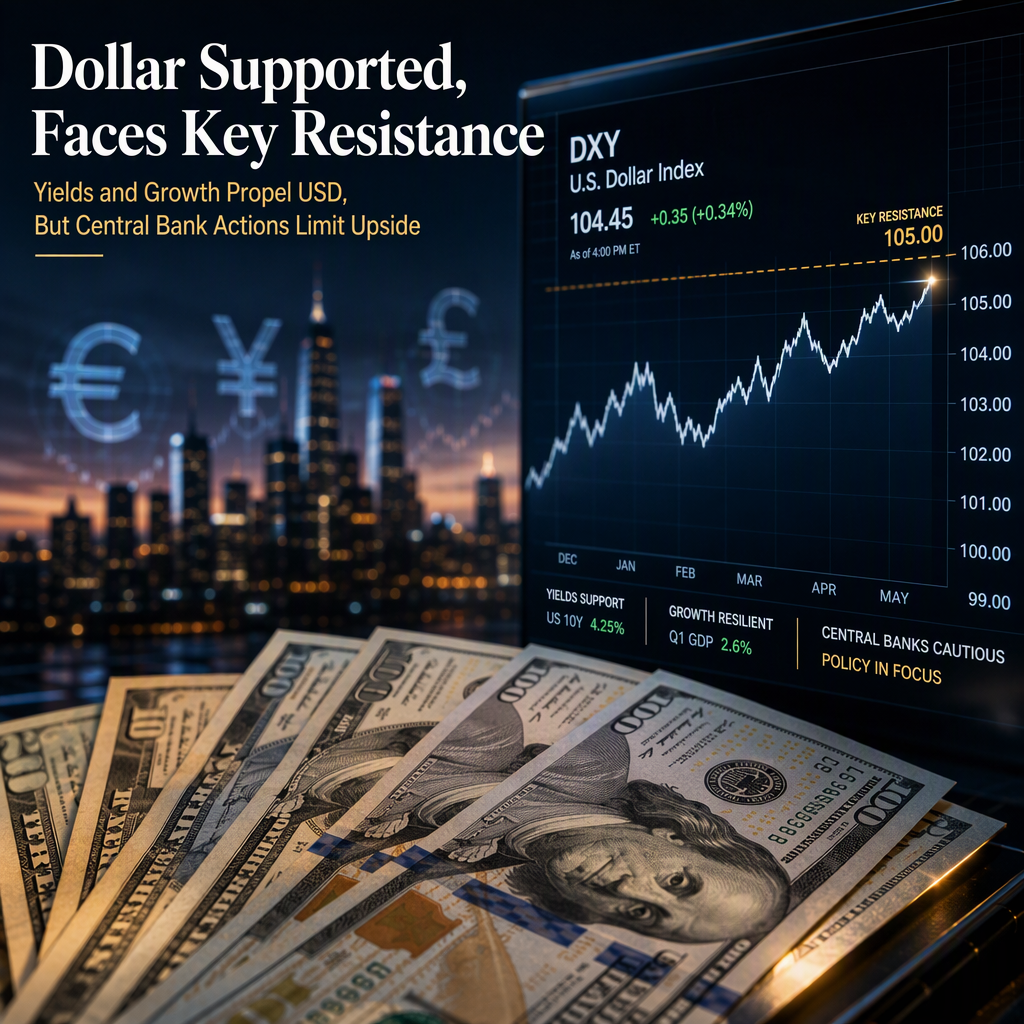
According to Elias Haddad at Brown Brothers Harriman, the US Dollar (USD) continues to receive support from widening US-G6 interest rate differentials and rising US longer-term real yields [1]. These factors are seen as positive drivers for the currency, with US economic growth outperformance and strong foreign demand for US securities further underpinning the Dollar's strength [1].
However, the report notes that tightening by other major central banks is limiting the extent of policy divergence with the Federal Reserve. This development suggests that the DXY index may struggle to sustain a break above its June 24 high at 101.80, despite the supportive backdrop of US growth and asset demand [1].
The analysis highlights a nuanced outlook: while the Dollar has fundamental support, the upside appears constrained due to global central bank actions. No specific market reactions or analyst forecasts beyond these observations are provided in the source [1].
CONCLUSION
The US Dollar remains fundamentally supported by higher yields and economic growth, but faces resistance due to narrowing policy divergence with other central banks. The DXY index may find it difficult to sustain levels above its recent high, reflecting a balanced but cautious market outlook.