
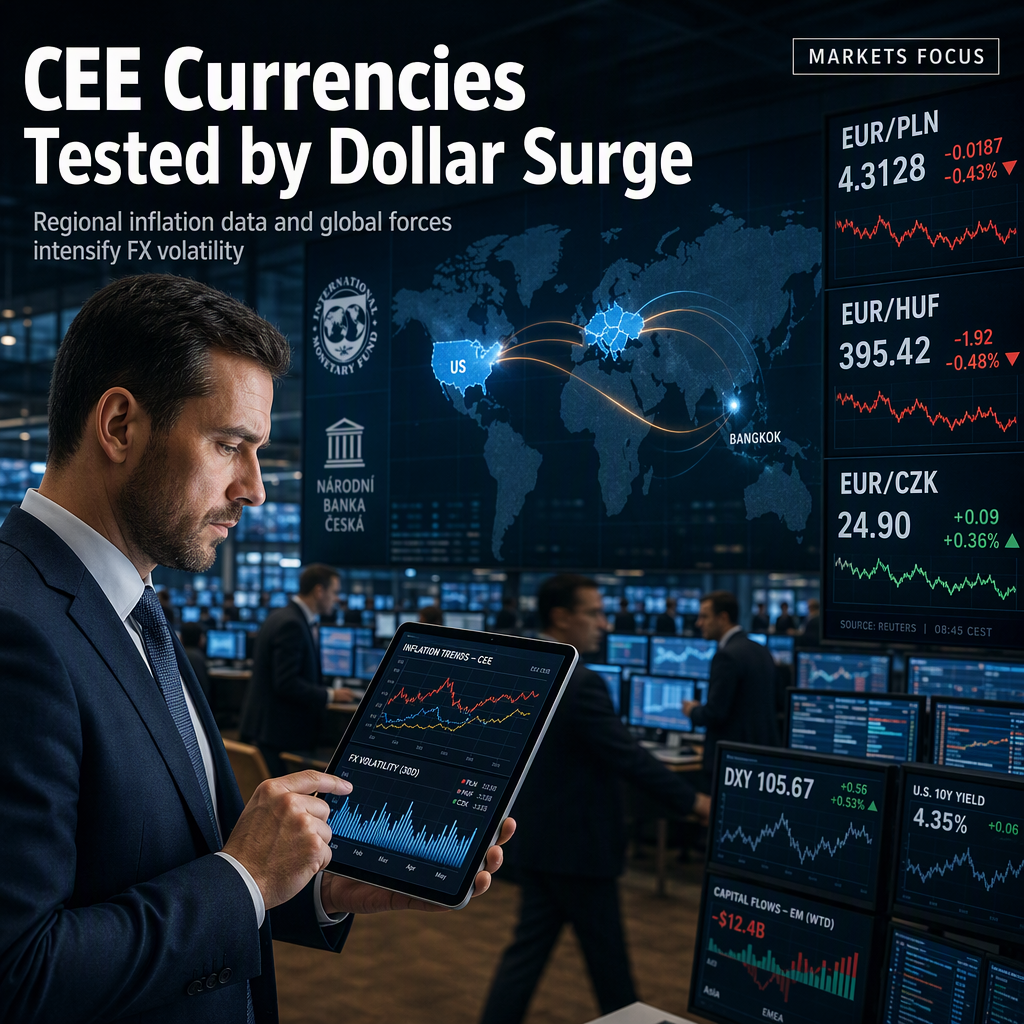
Central and Eastern European (CEE) currencies are navigating a pivotal week marked by significant regional inflation data releases and the influence of global foreign exchange trends, according to ING’s Frantisek Taborsky [1]. ING maintains a broadly bearish outlook on CEE currencies, citing the dominance of global factors such as US dollar strength and higher energy prices over regional developments [1].
Key inflation figures are expected across the region. Romania’s September inflation is anticipated to rise from 6.2% to 6.4%, with further increases likely through the end of the year, in line with recent central bank guidance [1]. In the Czech Republic, final data should confirm September inflation at 2.5%, while core inflation is projected to edge up from 3.0% to 3.1-3.2%, remaining above the central bank’s forecast [1]. Poland’s headline inflation is expected to be confirmed at 4.0%, with core inflation likely dropping from 3.3% to 3.1%, potentially providing the National Bank of Poland with greater policy flexibility [1]. Hungary will release wage data on Friday, with wage growth continuing to pose inflationary risks relative to the region [1].
Market attention is also turning to the IMF meetings in Bangkok, where CEE officials are expected to participate, and Hungary may publish its draft budget and medium-term fiscal outlook later in the week [1]. Following the recent National Bank of Poland meeting, the EUR/PLN exchange rate rose into the anticipated 4.380-4.400 range and is expected to remain near the upper end in the coming days [1]. The Hungarian forint is awaiting the government’s 2027 budget announcement but remains vulnerable to external pressures, particularly energy prices and the US dollar [1]. In contrast, the Czech koruna stands out as an exception, supported by a wider interest-rate differential, with ING retaining a bullish view and expecting EUR/CZK to move towards 24.250 [1].
CONCLUSION
CEE currencies are under pressure from global factors, especially the strong US dollar and rising energy prices, despite upcoming regional inflation data and policy events. ING’s outlook remains bearish for most CEE currencies, with the Czech koruna as a notable exception due to supportive interest-rate differentials. Market participants are closely watching inflation releases, central bank moves, and fiscal announcements for further direction.