
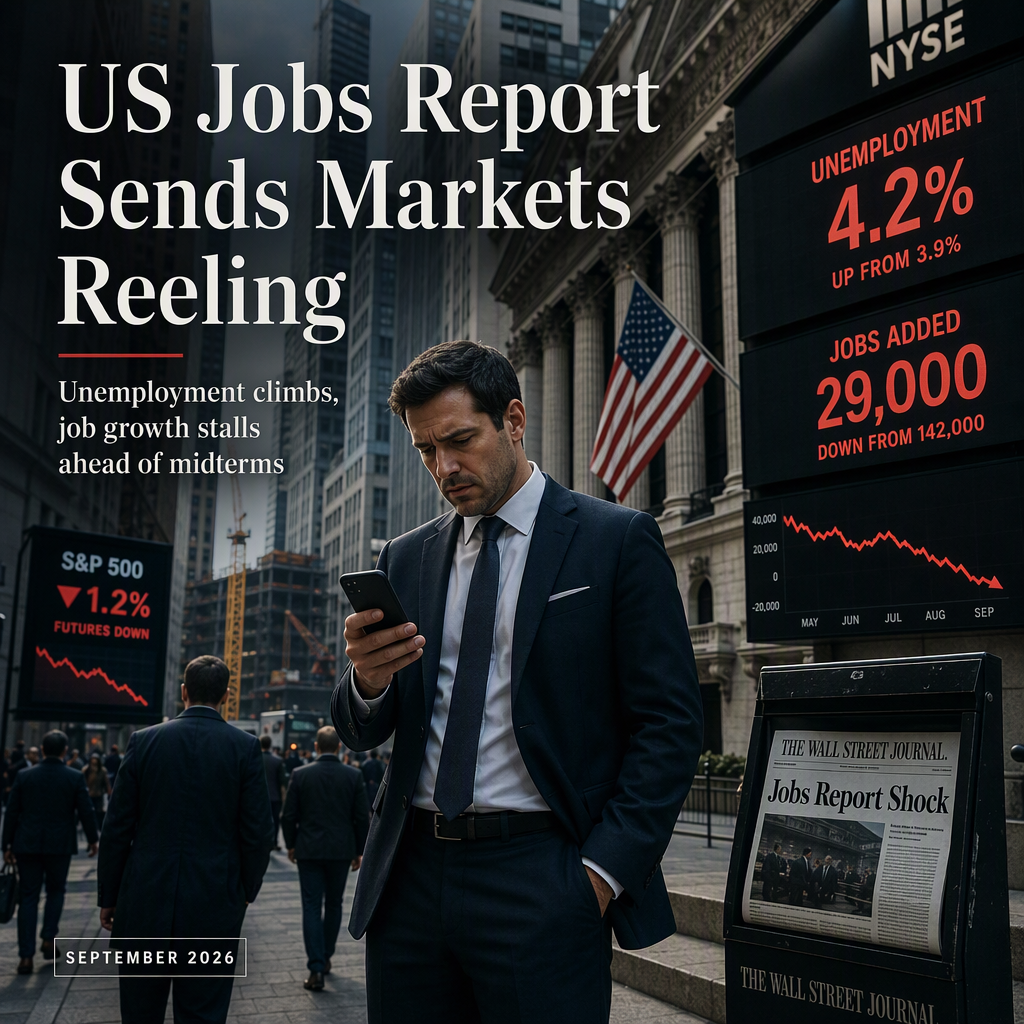
The U.S. economy added just 29,000 jobs in September 2026, significantly below economist expectations, which ranged from 84,000 to 90,000 according to Dow Jones and LSEG polls [1][2][3]. The unemployment rate increased to 4.2%, also above the anticipated 4.1% [1][2][3]. The Bureau of Labor Statistics revised previous months' payroll numbers downward: July shifted from a gain of 21,000 to a loss of 10,000, and August was revised from a gain of 162,000 to 133,000, resulting in 60,000 fewer jobs than previously reported [1][2][3].
Sector breakdowns show private payrolls grew by 46,000 in September, well below the 85,000 estimate, while government payrolls contracted by 17,000 jobs [1]. Healthcare led gains with 17,000 new jobs, though at a slower pace than the prior 12-month average [2]. Construction jobs rose by 11,000, driven by demand for skilled workers in AI data center projects [2]. Manufacturing added 9,000 jobs, just shy of expectations [1]. Average hourly earnings increased only 0.1% month-over-month and 3% year-over-year, marking the sixth consecutive month of wage growth lagging inflation [2].
Markets responded swiftly to the report. Stock futures jumped and Treasury yields fell, as traders interpreted the weaker jobs data as reducing the likelihood of a Federal Reserve rate hike at its October meeting [2][3]. Market-implied odds of the Fed holding rates steady at the Oct. 27-28 meeting surged to 83.7% [3]. Economist Thomas Simons of Jefferies commented, "For the Fed, this number should be the nail in the coffin for an October hike" [3].
The household survey, which calculates the jobless rate, showed stronger figures than the establishment survey: household employment rose by 406,000, the labor force grew by 485,000, and the participation rate increased to 61.8%, its highest since May [3]. An alternative unemployment measure, including discouraged and part-time workers, edged down to 7.6%, its lowest since January 2025 [3].
Political and economic context was also noted, as September's jobs report is the final monthly employment data before the U.S. midterm elections. The report comes amid ongoing trade wars, elevated gas and diesel prices, and surging global bond yields, with the average 30-year fixed mortgage rate reaching 7.6% [2]. Democrats are expected to use the weaker jobs data to criticize President Donald Trump and the Republican Party on economic performance [2].
CONCLUSION
September's jobs report revealed a marked slowdown in U.S. job growth and a rise in unemployment, prompting markets to anticipate a pause in Federal Reserve rate hikes. The weaker labor data, combined with downward revisions to previous months, heightened concerns about the economy's trajectory and will likely influence both monetary policy and political debates ahead of the midterm elections.