
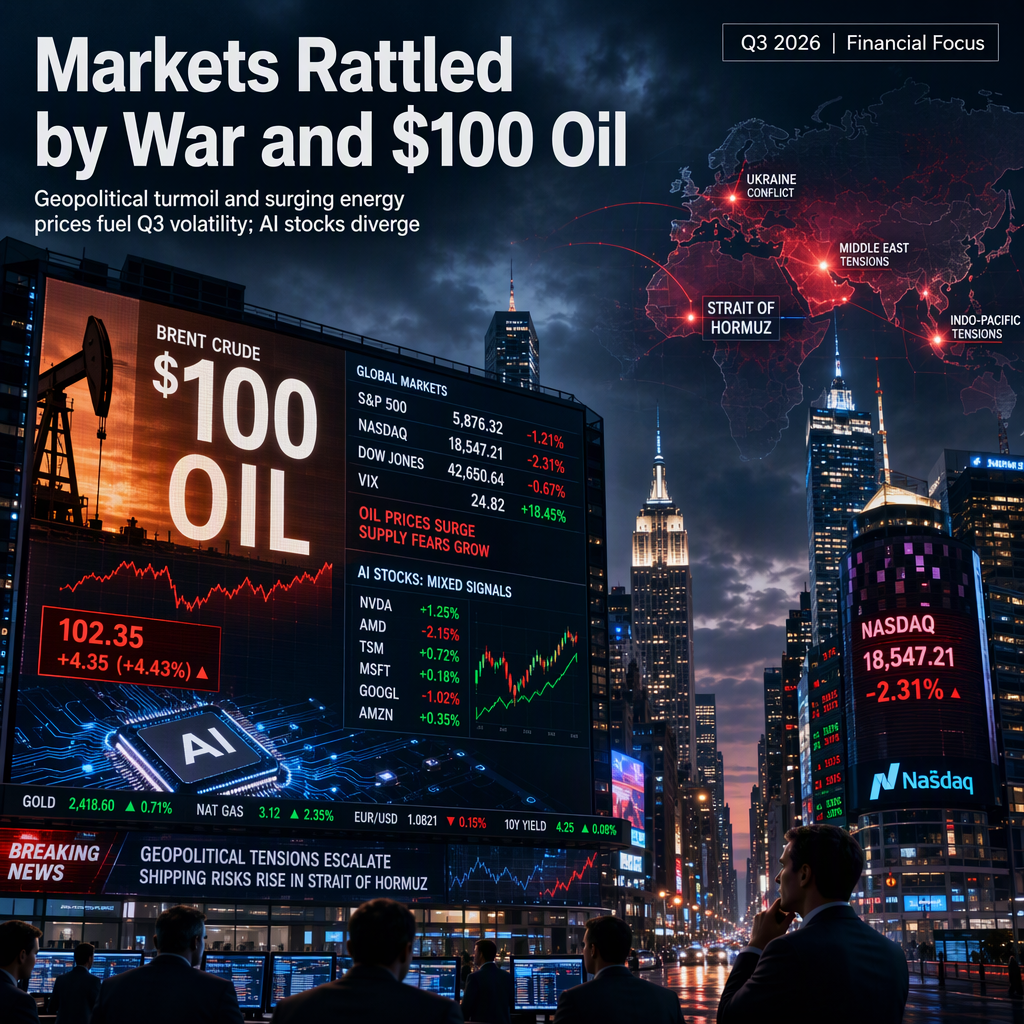
The third quarter of 2026 was marked by significant volatility in global financial markets, driven by the ongoing war between the U.S., Israel, and Iran, as well as a sharp surge in oil prices. The conflict, which saw the Strait of Hormuz remain blocked, heightened fears of energy market disruptions and inflation. U.S. President Donald Trump vowed to inflict 'Economic D-Day' on Tehran and reportedly rejected an Iranian ceasefire proposal, contributing to market uncertainty [1].
Despite these geopolitical tensions, Wall Street's major averages ended the quarter with mixed results. The S&P 500 index rose by 2.03%, the Nasdaq Composite gained 2.2%, while the Dow Jones Industrial Average fell by 1.9%. The average change across these indexes was just 0.6%, a notable slowdown compared to the double-digit gains seen in the previous quarter [1].
The artificial intelligence sector experienced significant turbulence. July saw sell-offs due to profit-taking after Samsung's record earnings and concerns about competition from China. In August, AI stocks faced volatility amid worries over financing and capital expenditure. September brought further pressure as prominent AI leaders, including Anthropic chief Dario Amodei and OpenAI CEO Sam Altman, called for a slowdown in AI development due to safety concerns [1].
Performance among AI heavyweights was mixed: Nvidia shares gained over 14%, Microsoft surged 37.5%, and Meta stock jumped nearly 30% following the successful launch of its Muse AI personal agent. In contrast, Oracle and Broadcom both lost more than 6%. The Philadelphia Semiconductor Index dropped over 11%, and South Korea's Kospi index fell 19.3%. Mainland China's CSI 300 shed 12.5%, while Australia's S&P/ASX 200 was flat. The MSCI Emerging Markets index declined by 1%, though some country-specific MSCI indexes posted double-digit gains [1].
Despite the headwinds, investor optimism persisted, buoyed by AI and corporate earnings expectations, which helped offset some of the negative impacts from geopolitical risks and energy market fears [1].
CONCLUSION
The third quarter of 2026 saw markets grapple with geopolitical turmoil and surging oil prices, resulting in heightened volatility and mixed equity performance. While AI and select tech stocks delivered strong gains, broader market momentum slowed compared to earlier in the year. Investor sentiment remained cautiously optimistic, supported by robust earnings in key sectors.