
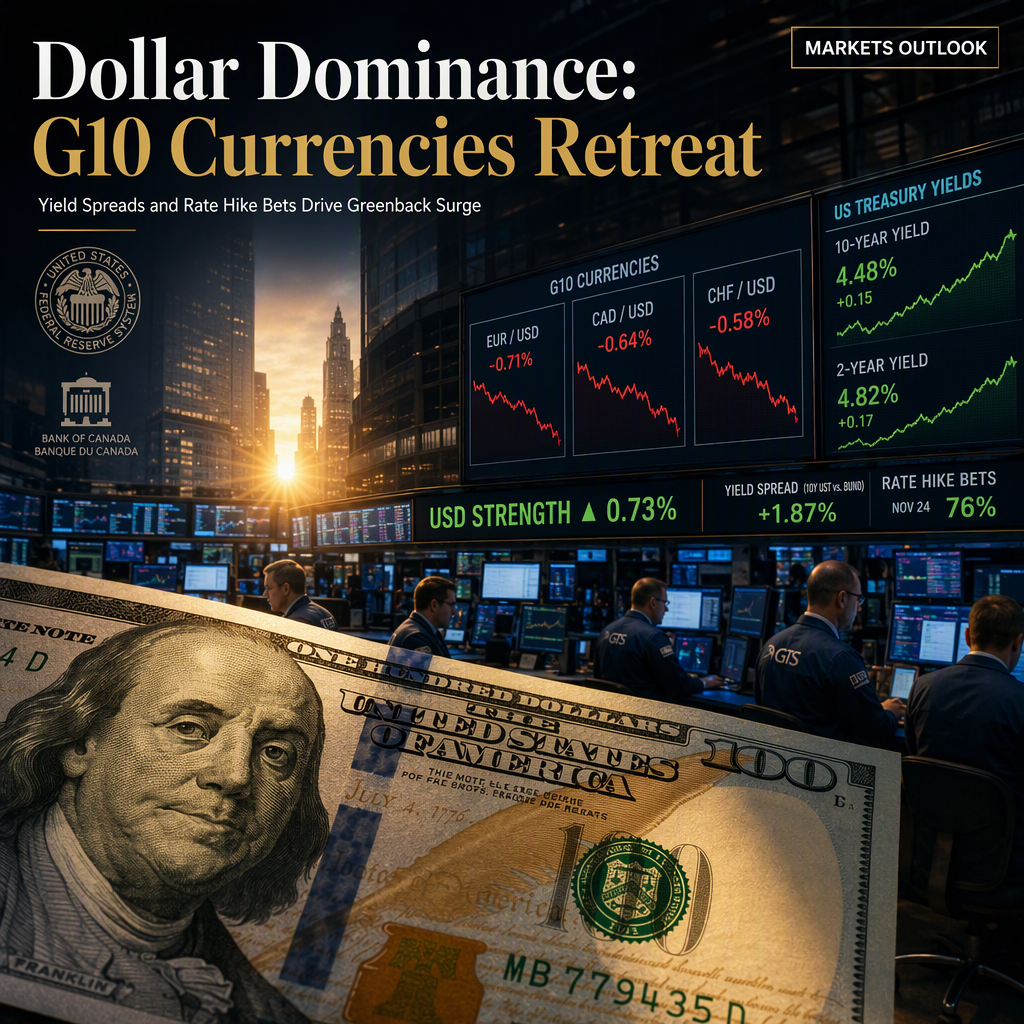
The US Dollar (USD) has demonstrated broad strength against most G10 currencies, driven by widening US-Canada yield spreads and firm expectations for further tightening by the Federal Reserve and the Bank of Canada (BoC) [1][2][4]. Scotiabank analysts estimate the fair value for USDCAD at 1.4068, citing persistent headwinds for the Canadian Dollar (CAD) due to wider yield spreads and firming BoC rate hike expectations, with October priced for 14 basis points and December for a cumulative 37 basis points of tightening [1]. The upcoming Canadian GDP data for July is expected to show a flat month-over-month print and a slowdown in annual growth from 2.0% to 1.4% [1].
The DXY index has moved in tandem with its fair value estimate based on 2-year yield spreads, currently at 100.5, with spot just above 101. The index is approaching its June 24 high, which marked the local peak and 2026 year-to-date high [2]. US bond yields remain well supported, with the 10-year Treasury yield extending above 5.2% to its highest level since 2007, contributing to a defensive tone in G10 currencies and mild risk aversion in equity markets [2].
In the cross-currency space, the Euro (EUR) has softened against the Canadian Dollar, with EUR/CAD trading around 1.6100, halting a three-day winning streak. This move is attributed to caution from the European Central Bank (ECB) and strength in oil prices, which support the CAD. Geopolitical risks, particularly surrounding US-Iran negotiations and Middle East hostilities, continue to influence oil markets and, by extension, the CAD [3]. Despite recent oil market gains, investor positioning in the CAD has turned more negative, with Rabobank noting a renewed build-up in net shorts after a previous decline [3].
The Swiss Franc (CHF) has extended losses for a fifth consecutive day against the USD, with USD/CHF trading at 0.8330, just below the 16-month high of 0.8339. This decline comes despite a strong KOF Leading Indicator reading of 109.1 for September, the highest in six years and above expectations of 105.8 [4]. The USD's strength is underpinned by robust macroeconomic data, higher Treasury yields, and expectations of at least one more Fed rate hike before year-end, as affirmed by Fed Governor Lisa Cook [4]. Rabobank strategists report that USD net longs remain largely unchanged, while market-derived rate expectations suggest investors anticipate more than three Fed hikes by the end of next year [4].
CONCLUSION
The US Dollar continues to outperform G10 peers, supported by widening yield spreads, strong macroeconomic data, and expectations of further rate hikes by both the Federal Reserve and the Bank of Canada. Despite some positive economic indicators in other regions, such as Switzerland, the USD's momentum remains dominant, driving defensive positioning in other major currencies. Market sentiment is tilted toward further USD strength in the near term.