
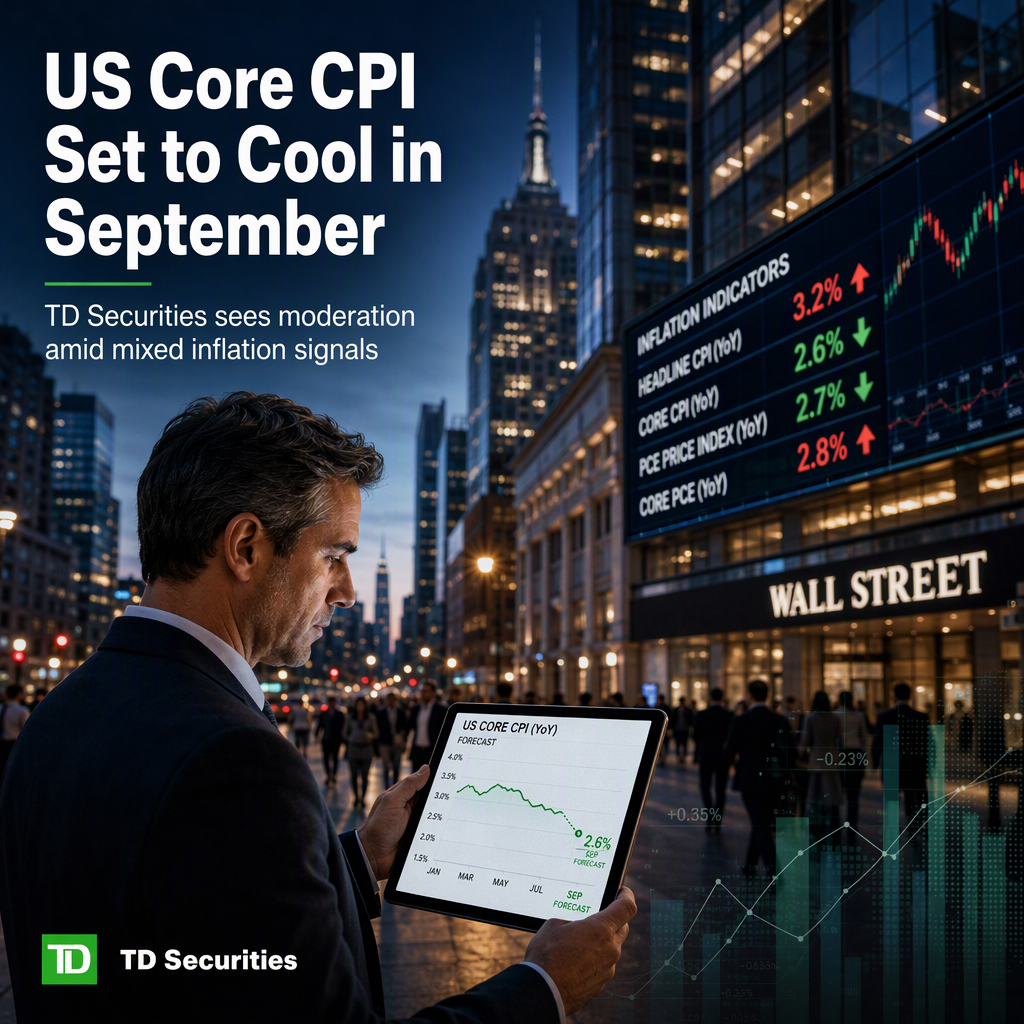
TD Securities' US economics team, led by Oscar Munoz, projects that the September Core CPI will slow to 0.20% month-on-month, primarily due to softer core services and supercore components. The supercore segment is expected to moderate to 0.24% m/m, following an uptick in August, while core goods are anticipated to pick up slightly, driven by vehicle prices. Shelter inflation is forecasted to rebound modestly after a weak performance in August [1].
Year-on-year, the Core CPI is expected to remain broadly unchanged at 2.4%, though TD Securities notes upside risks stemming from discretionary services and AI-related goods. Specifically, discretionary services are forecasted to show strength, with lodging and airfares rising by 1.4% and 2.1%, respectively. Core services inflation is expected to edge lower to 0.22% m/m, offset by a subtle rebound in shelter [1].
The forecast translates to a 0.23% m/m increase in core PCE, only slightly below the 0.25% rise seen in August. TD Securities suggests that, given the Federal Reserve's established gradual hiking cycle, the September inflation reading is unlikely to significantly alter the outlook. Despite the moderation, core services inflation remains elevated, which could sustain the Fed's concerns about inflation risks [1].
Looking ahead, TD Securities expects the core segment to bottom at 2.4% y/y and end 2026 at 2.7% y/y. Headline inflation is projected to gradually rise, ending 2026 at 3.9% after peaking at 4.2% in May. The trajectory of headline inflation will depend on the resolution of the Middle East conflict, with further progress anticipated by mid-2027 [1].
CONCLUSION
TD Securities anticipates a moderation in US core CPI for September, with inflation risks persisting in certain segments. The Federal Reserve's outlook is expected to remain largely unchanged, as core services inflation stays elevated. Longer-term projections suggest gradual increases in both core and headline inflation, contingent on geopolitical developments.