
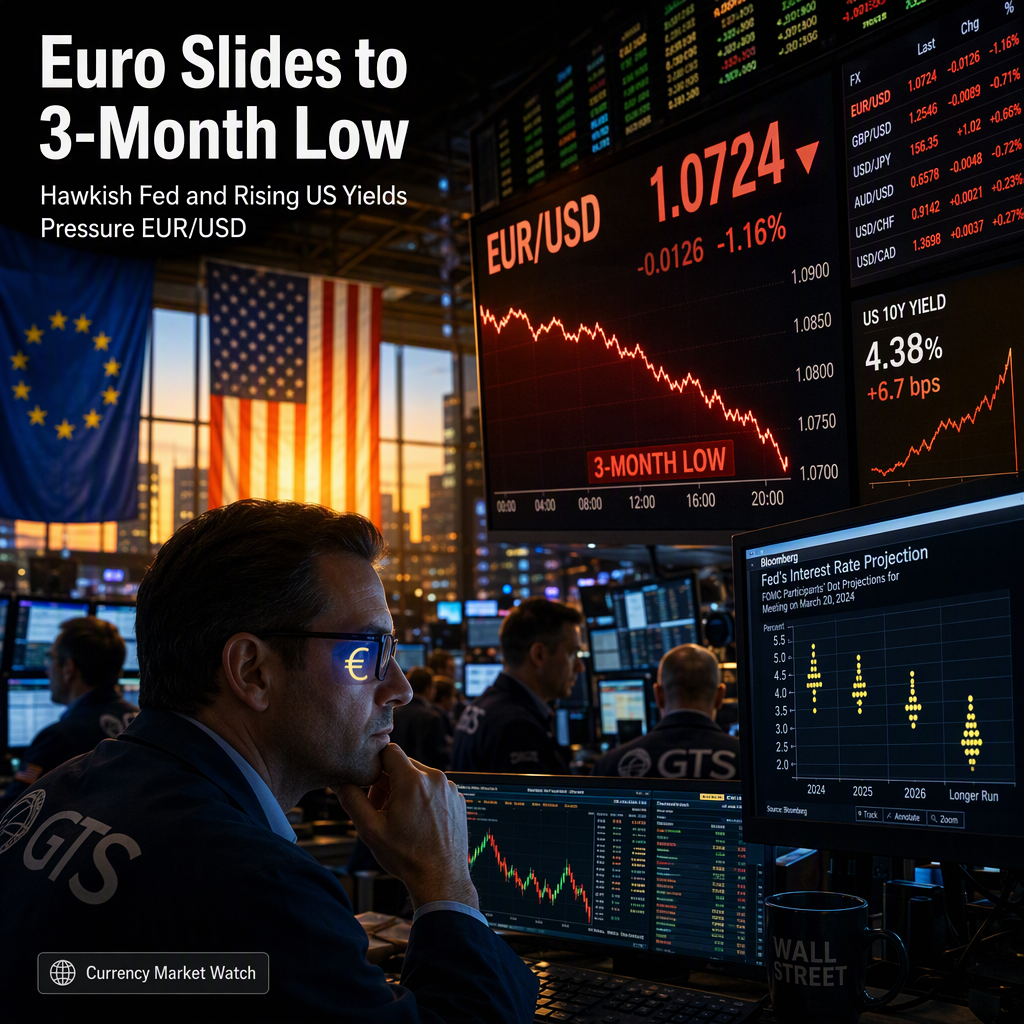
The Euro (EUR) extended its decline against the US Dollar (USD) on Tuesday, with the EUR/USD pair falling to its lowest level since late June and trading around 1.1331, down 0.35% on the day [1]. This move was driven by broad-based US Dollar strength, which persisted despite weaker-than-expected US economic data. The US Dollar Index (DXY) reached 101.50, its highest level in two months, reflecting continued demand for the Greenback [1].
US economic data released on Tuesday showed JOLTS Job Openings fell to 7.079 million in August, below the market forecast of 7.23 million, and the Conference Board Consumer Confidence Index dropped to 81.9 in September, missing expectations of 89.0. Despite these softer data points, traders remained focused on the inflationary impact of elevated oil prices and the resulting hawkish outlook for the Federal Reserve (Fed) [1]. According to the CME FedWatch Tool, markets are pricing in a 68% probability of another interest-rate increase at the Fed’s October meeting, following a 25-basis-point hike earlier this month [1].
Expectations of higher US interest rates and heightened inflation risks have pushed US Treasury yields to multi-year highs, with the benchmark 10-year yield climbing to 5.28%, its highest level since 2007. This has increased the appeal of Dollar-denominated assets and widened the interest-rate gap between the United States and the Eurozone, adding further pressure on EUR/USD [1].
On the European side, traders also anticipate further interest rate hikes by the European Central Bank (ECB) this year. Recent ECB communication indicates that inflation risks remain tilted to the upside due to elevated oil prices, though policymakers have not observed clear signs of second-round effects. However, higher energy costs are seen as posing downside risks to economic growth, presenting a challenging policy trade-off for the ECB [1].
Looking ahead, market participants are focused on upcoming US data releases, including the Personal Consumption Expenditures (PCE) Price Index, ISM Manufacturing Purchasing Managers’ Index (PMI), Nonfarm Payrolls (NFP), and preliminary Eurozone inflation data for September, which could further influence currency movements [1].
CONCLUSION
The Euro's drop to a three-month low against the US Dollar reflects persistent market expectations for higher US interest rates and rising Treasury yields, which have strengthened the Dollar despite softer US economic data. The ECB faces a complex policy environment as it balances inflation risks with potential economic headwinds from higher energy costs. Upcoming US and Eurozone data releases will be closely watched for further market direction.