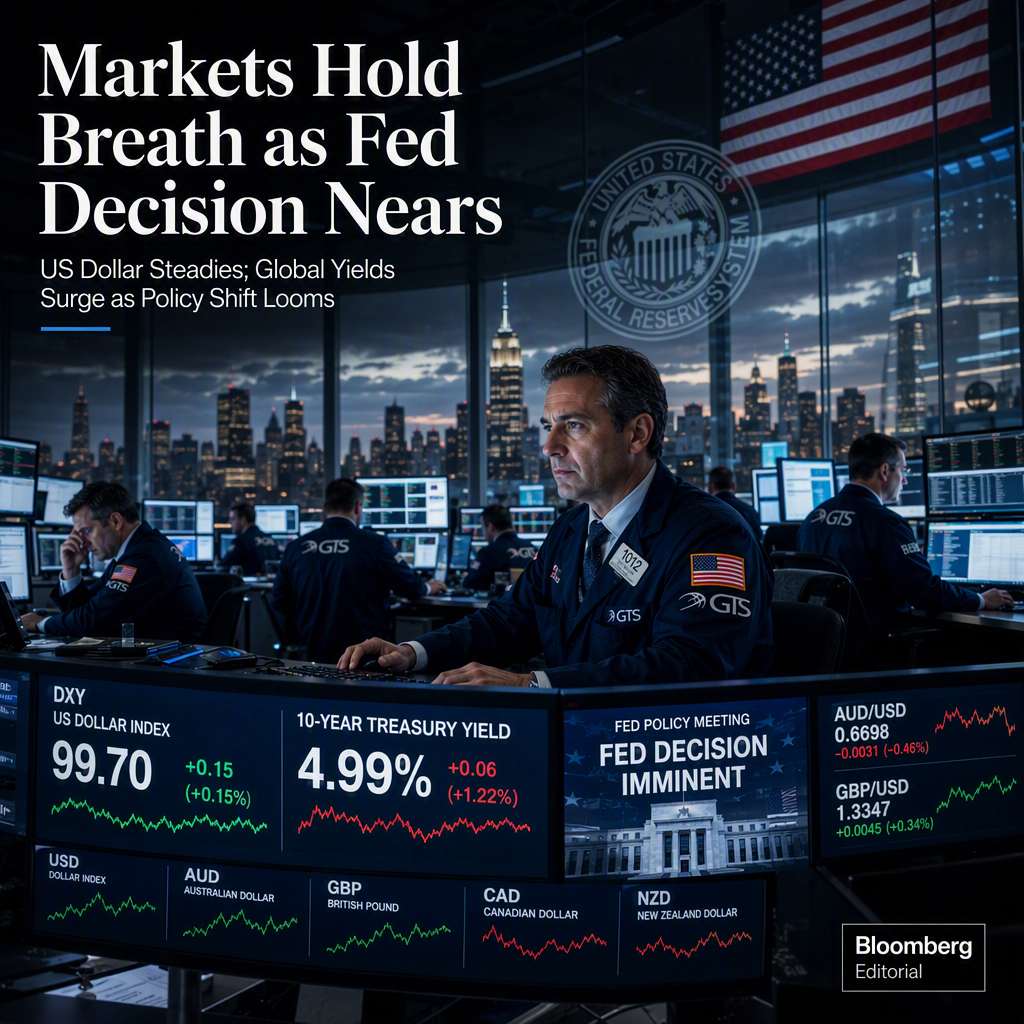
On Wednesday, global financial markets are trading cautiously ahead of the US Federal Reserve's (Fed) monetary policy announcement, with the US Dollar (USD) holding near a two-week high at around 99.60-99.70 on the Dollar Index (DXY) [1][2]. The benchmark 10-year US Treasury yield is trading at 4.992%, having attempted to retest the 5% mark, its highest since 2007 [2]. Markets are pricing in a 92.4% probability that the Fed will raise interest rates by a quarter of a percentage point at its September policy meeting, according to the CME FedWatch tool [2][3]. Commerzbank analysts expect that the latest upside surprise in US inflation will likely prompt a majority on the FOMC to vote for a rate increase, which could bolster the Fed's credibility [1]. However, they note that market reaction will depend not only on the rate decision but also on updated projections, particularly the 'dot plot,' which could signal further hikes and potentially strengthen the US Dollar [1][3].
The AUD/USD pair is trading slightly lower at around 0.7125, maintaining a mildly bearish tone as it sits below the 20-period EMA at 0.7152. Technical analysis suggests fading bullish momentum, with immediate resistance at 0.7152 and support near 0.7108; a failure to hold support could expose the pair to 0.7050 [1]. The US Dollar was the strongest against the Canadian Dollar, up 0.07%, and gained 0.05% against both the Australian and New Zealand Dollars, according to the day's currency heat map [2]. Analysts at MUFG attribute the Dollar's firmness to rising US yields, noting the 10-year yield has risen by more than 80 basis points since the start of the year [2].
In the UK, the British Pound (GBP) remains on the defensive, retreating to 1.3480 against the USD after UK CPI data for August met expectations. Headline CPI rose to 3.1% YoY from 2.9% in July, while core CPI held steady at 2.6% YoY [3][4]. Producer prices outpaced forecasts, with input PPI at 6.1% YoY and output PPI at 3.7% YoY [3]. Despite the inflation uptick, the Bank of England (BoE) is widely expected to keep its benchmark rate at 3.75% for a sixth consecutive meeting, with strategists at Brown Brothers Harriman anticipating a 6-3 vote in favor of holding rates [4]. Recent comments from Governor Bailey have dampened hopes for immediate tightening, though some strategists expect a minority to back a 25bps hike [3][4].
Looking ahead, the market focus is on the Fed's updated projections and Chair Kevin Warsh's press conference, as his distaste for forward guidance means investors will scrutinize the 'dot plot' for clues on future hikes [3]. TD Securities analysts suggest the dot plot may show fewer hikes than markets anticipate, which could trigger 'knee-jerk weakness' in the US Dollar immediately after the announcement [3]. Meanwhile, the BoE's policy decision is scheduled for Thursday, with consensus expecting rates to remain unchanged at 3.75% [4].
CONCLUSION
Markets are trading with heightened caution as the Fed is expected to raise rates, with the US Dollar holding near recent highs and yields climbing. The British Pound remains pressured despite rising UK inflation, as the BoE is seen holding rates steady. The outcome of the Fed's policy meeting and its projections will be pivotal for near-term currency and yield movements.