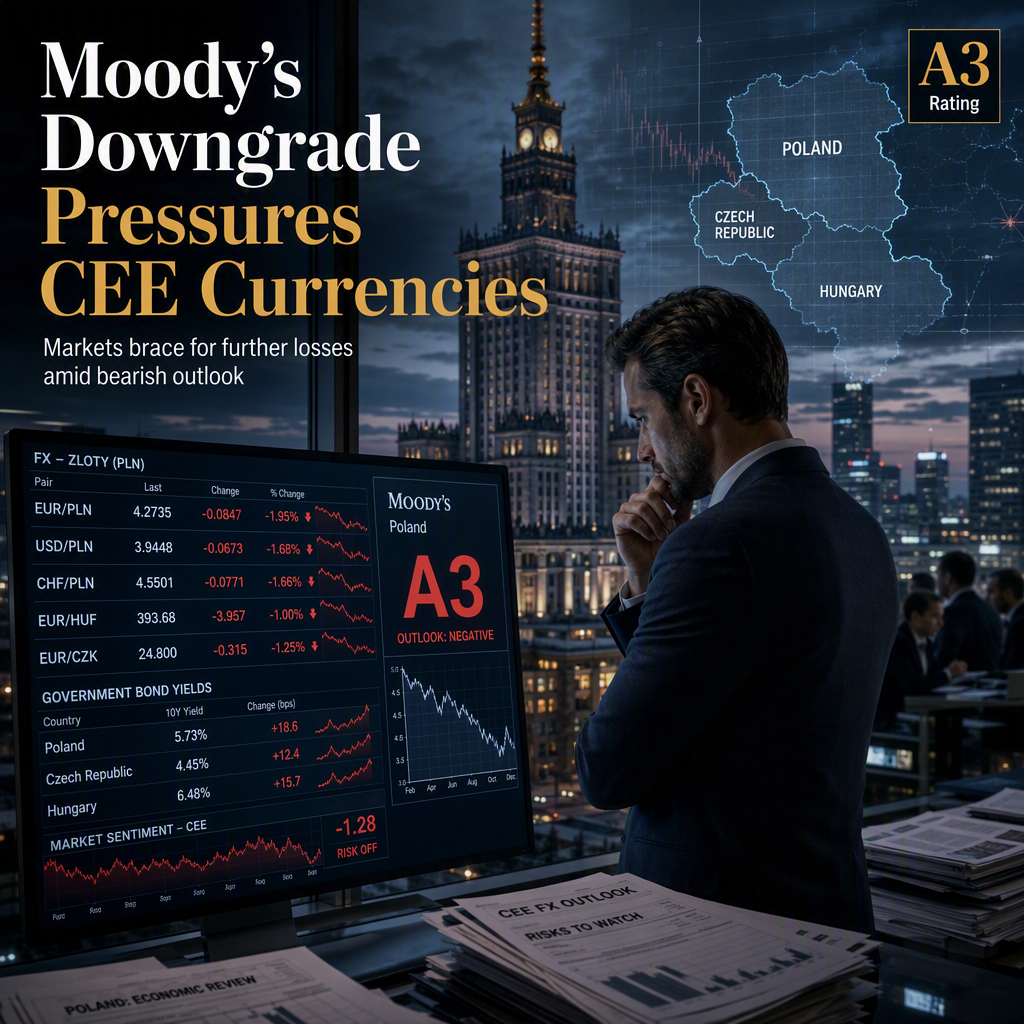
Moody’s downgraded Poland’s credit rating to A3, aligning it with S&P and Fitch, which ING strategist Frantisek Taborsky notes is adding pressure to Central and Eastern European (CEE) assets at the start of a typically quiet second half of the month [1]. ING maintains a bearish view on CEE currencies, citing persistent headwinds such as high energy prices, a stronger US Dollar, and limited progress in the US-Iran conflict [1].
The downgrade is expected to result in some aversion to Polish bonds, although ING suggests that bond markets may have partly priced in the move already [1]. Key upcoming events include Poland’s August wage data and retail sales, as well as the National Bank of Hungary (NBH) meeting, where the central bank is expected to pause its current 'mini' easing cycle and keep the policy rate at 5.50%. The NBH will also publish a new forecast and may review its inflation target, potentially outlining a two-step reduction from 3.0% to 2.0% [1].
ING sees fair value for EUR/CZK at 24.300–24.350 and anticipates further upside risk in EUR/PLN following the downgrade, with today serving as an early test for the Polish zloty [1]. For the Hungarian forint, EUR/HUF could rise in the near term, but the NBH meeting may provide temporary support, potentially pulling the pair back towards 362 [1].
In the Czech Republic, consumer demand data is due on Thursday, followed by the Czech National Bank minutes on Friday, which are expected to provide more detail on last week’s board discussion [1]. Overall, CEE currencies remain weak, and ING retains a bearish outlook for the week ahead, with external factors continuing to hinder any recovery [1].
CONCLUSION
Moody’s downgrade of Poland to A3 has intensified pressure on CEE currencies, with ING maintaining a bearish outlook due to ongoing macroeconomic challenges. Market participants are closely watching upcoming central bank meetings and economic data for further direction, but no immediate recovery is expected for regional FX.