
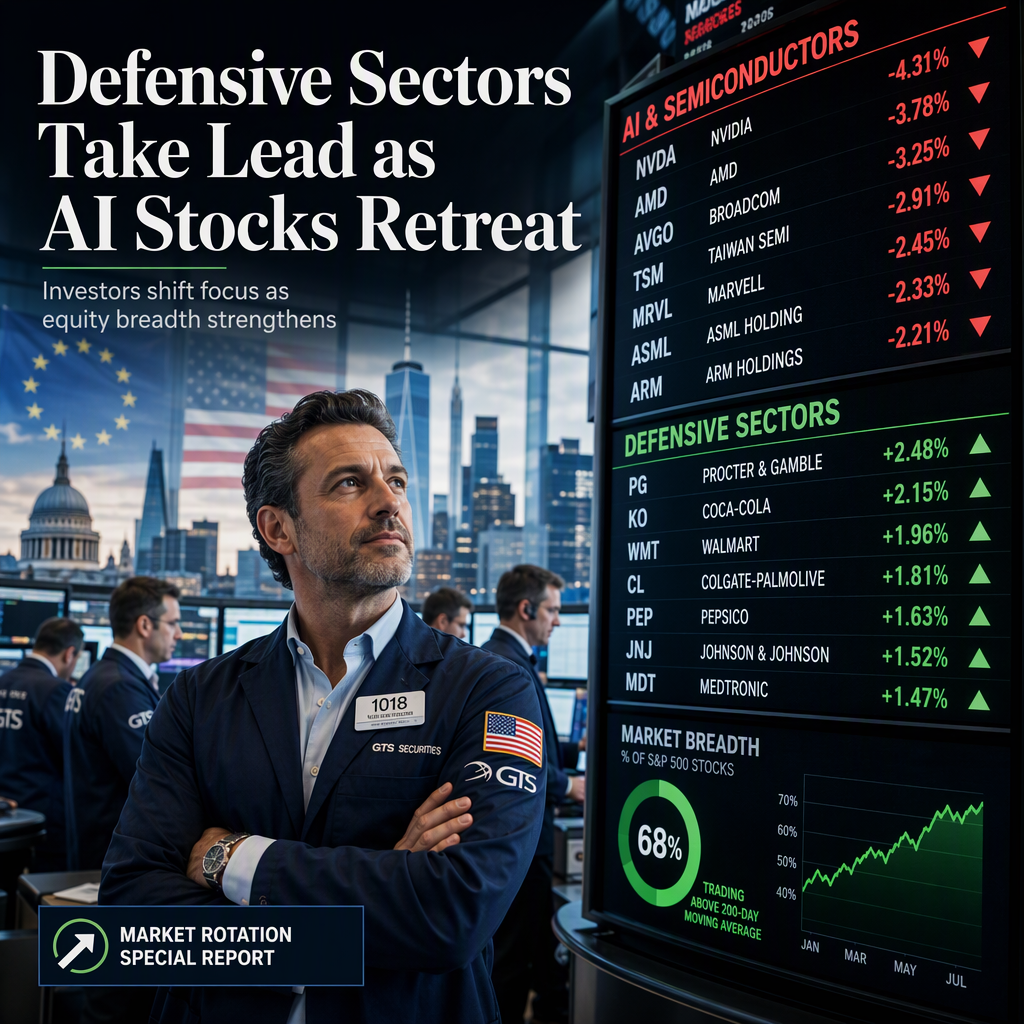
Global equities ended broadly flat on Monday, but this headline figure masked significant sector rotation as investors reduced their exposure to AI and semiconductor stocks, which have been among the strongest performers this year [1]. Europe and defensive sectors, particularly consumer staples, outperformed during this period [1]. The S&P 500 saw a marginal decline, yet market breadth remained robust, with 321 constituents advancing compared to 179 declining. This marked the seventh session in eight with positive breadth and another day of outperformance for the equal-weighted index, challenging the narrative that US market leadership is narrowly concentrated and signaling that a broader correction may not be imminent [1].
The rotation away from AI and semiconductors persisted into the following morning, with Korea's KOSPI index down approximately 7% [1]. European and US futures were described as mixed, with defensive sectors providing support while AI and semiconductor stocks continued to face pressure [1].
Danske Bank's research team cautioned against drawing historical parallels, noting that recent market leadership has been driven by substantially stronger earnings growth rather than relative multiple expansion. This distinction is important when assessing the vulnerability of current market leaders [1].
CONCLUSION
The market is experiencing a notable shift as investors move away from AI and semiconductor stocks toward defensive sectors, resulting in strong breadth and outperformance of equal-weighted indices. Despite pressure on high-growth sectors, defensive exposure is providing support, and the overall market remains resilient. This rotation suggests a cautious but stable outlook for equities, with no imminent signs of a broad correction.