
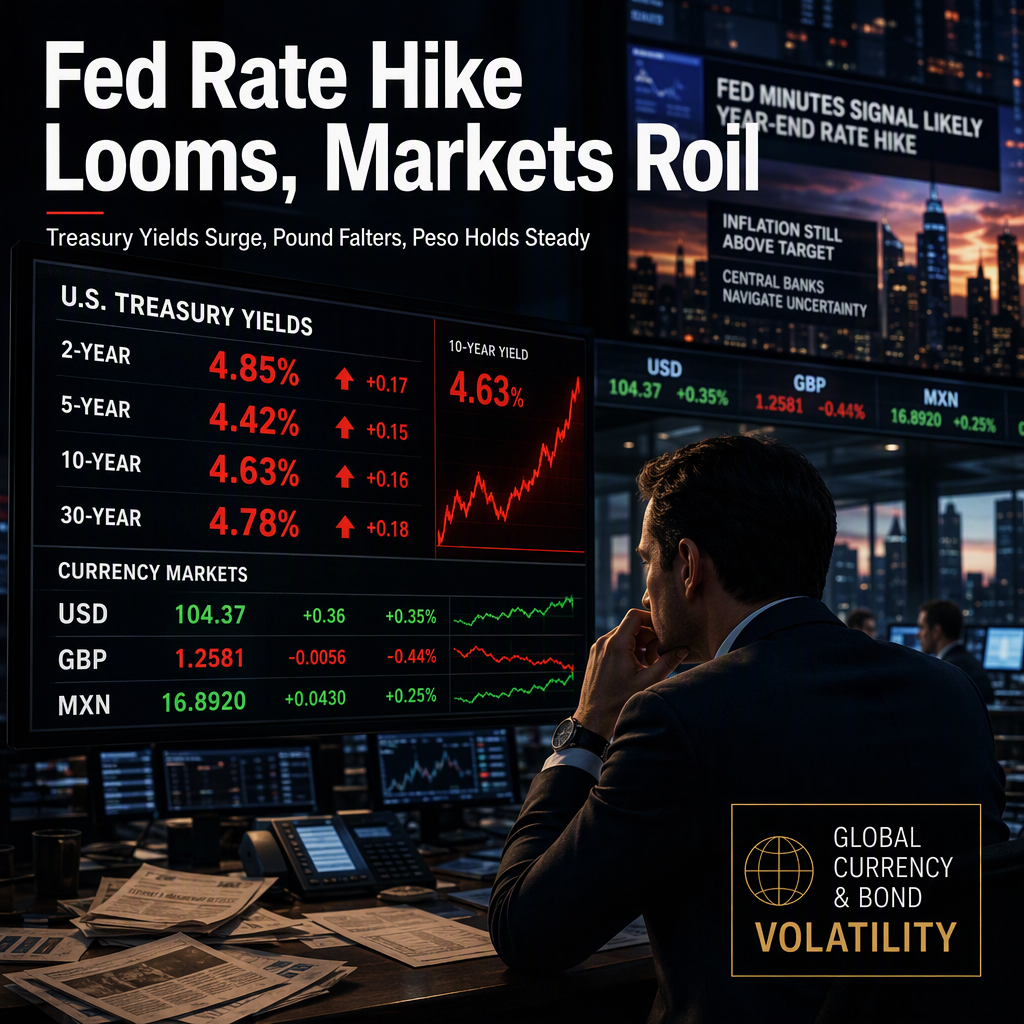
The release of the Federal Reserve's September meeting minutes revealed that all 19 participants supported the recent rate hike to 3.75%-4.00%, with most officials judging another increase likely to be appropriate by year end [1][2]. The minutes also highlighted a split among policymakers, with some viewing the September hike as precautionary and others seeing it as the start of a tightening cycle to combat persistent inflation above the 2% target for five years [2]. Money markets currently price an 81% chance of no Fed rate hike in October, with only a 19% probability of an increase [2].
The anticipation of further Fed tightening has had significant effects on currency and bond markets. The US Dollar strengthened as US Treasury yields rose, with Wednesday's 10-year Treasury auction clearing at 5.30%, the highest yield at a 10-year sale since November 2000 [1]. In the UK, the 30-year gilt yield climbed back above 6%, a level first reached on October 1 for the first time since 1998, raising Britain's borrowing costs [1]. The British Pound slid back to the bottom of its recent range, with GBP/USD trading just above 1.3200 and resistance at 1.3250, as the Dollar gained on higher yields [1]. Despite the bond selloff, the Pound remains at its strongest against the Euro since June 2025 [1].
In contrast, the Mexican Peso held firm against the US Dollar, with USD/MXN trading at 17.98, virtually unchanged after the Fed minutes [2]. The Peso had previously depreciated over 7% since September 21, reaching a high of 18.43 before retreating by over 2.3% [2]. The main driver of the Peso's weakness was the rise in US Treasury yields and speculation of further Fed rate hikes, which narrowed the interest-rate differential and reduced the appeal of the carry trade [2]. The Bank of Mexico has held rates steady, with economists projecting no change until the end of 2027 [2].
Looking ahead, traders are closely watching upcoming central bank meetings and economic data. The Fed's next policy decisions are scheduled for October 28 and December 9, with futures markets assigning a low probability to an October hike [1]. In the UK, the Bank of England is expected to meet on November 5, with traders pricing a November hike near 80% [1]. Key speeches from BoE officials and upcoming budget announcements could further influence market expectations [1]. In Mexico, September inflation figures and Banxico's meeting minutes are awaited, while in the US, Initial Jobless Claims and the University of Michigan's Consumer Confidence report are upcoming [2].
CONCLUSION
The Federal Reserve's minutes reinforced expectations of another rate hike by year end, driving volatility in global currency and bond markets. The US Dollar and Treasury yields rose, pressuring the British Pound and raising UK borrowing costs, while the Mexican Peso stabilized after recent losses. Market participants remain focused on upcoming central bank meetings and economic data for further direction.