
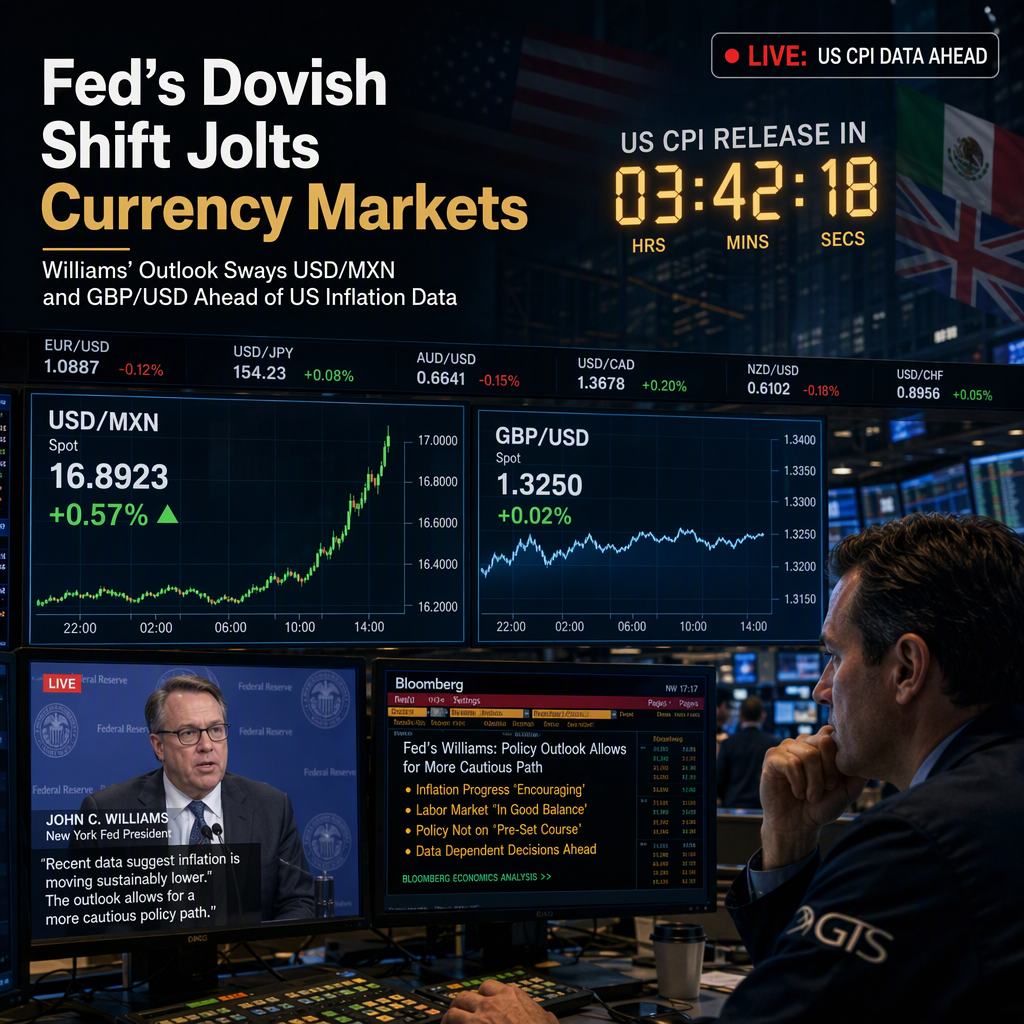
The US Federal Reserve's monetary policy outlook, particularly comments from New York Fed President John Williams, influenced currency markets as traders awaited the upcoming US Consumer Price Index (CPI) report for September. Williams indicated support for one more US rate hike in 2026 but none in 2027, a dovish stance that contrasted with more hawkish views from other Fed officials such as Boston Fed's Susan Collins and Chicago Fed's Austan Goolsbee, who expressed concerns about inflation pressures, particularly from AI-driven investment. Fed Governor Waller, while acknowledging these pressures, noted that inflation expectations remain well anchored and suggested that a cooling in AI investment could help lower inflation [1].
In the FX market, the Mexican Peso weakened against the US Dollar, with USD/MXN trading at 18.36, up 0.57%. This depreciation occurred despite the dovish rhetoric from Williams, as traders focused on the upcoming US CPI release, which is forecast to rise 0.6% month-over-month and 3.6% year-over-year, with core inflation expected at 0.2% MoM and 2.5% YoY [1]. Technical analysis showed USD/MXN extending its advance above key moving averages, with the Relative Strength Index at 70.9 indicating overbought conditions that could lead to consolidation. Immediate support levels were identified at 16.8866 and 17.3472 [1]. In Mexico, August industrial production improved to 3.5% YoY from 2.7%, but the economic calendar was otherwise light until upcoming retail sales and inflation data later in October [1].
Meanwhile, the British Pound gained against the US Dollar, with GBP/USD trading near 1.3250, in the middle of a range it has held since September 24. The Pound's rise was attributed to a weaker Dollar rather than Pound strength, as GBP/USD made a high after Williams's comments suggested the Fed could be done after one more hike. Futures markets, however, priced in about a 90% chance that the Fed's rate, currently at 3.75%-4.00%, would end 2027 at least half a point higher, implying two hikes, which is more hawkish than Williams's outlook [2]. The Pound showed little reaction to Bank of England (BoE) external member Greene's comments advocating for a UK rate hike, and GBP/USD remained below its 50-day and 200-day EMAs [2].
Looking ahead, the US CPI report for September is due, with forecasts at 3.6% YoY and core inflation at 2.5%. US retail sales data and UK GDP figures are also scheduled for release, which could influence future central bank decisions. BoE Chief Economist Pill and Governor Bailey, as well as Fed Chair Warsh, are set to speak later in the week, events that may further impact market sentiment [2].
CONCLUSION
Dovish signals from Fed President Williams contributed to a weaker US Dollar, benefiting the Pound but failing to support the Mexican Peso, which depreciated as traders focused on upcoming US inflation data. Market participants remain attentive to key economic releases and central bank commentary, which are likely to shape expectations for future interest rate moves.