
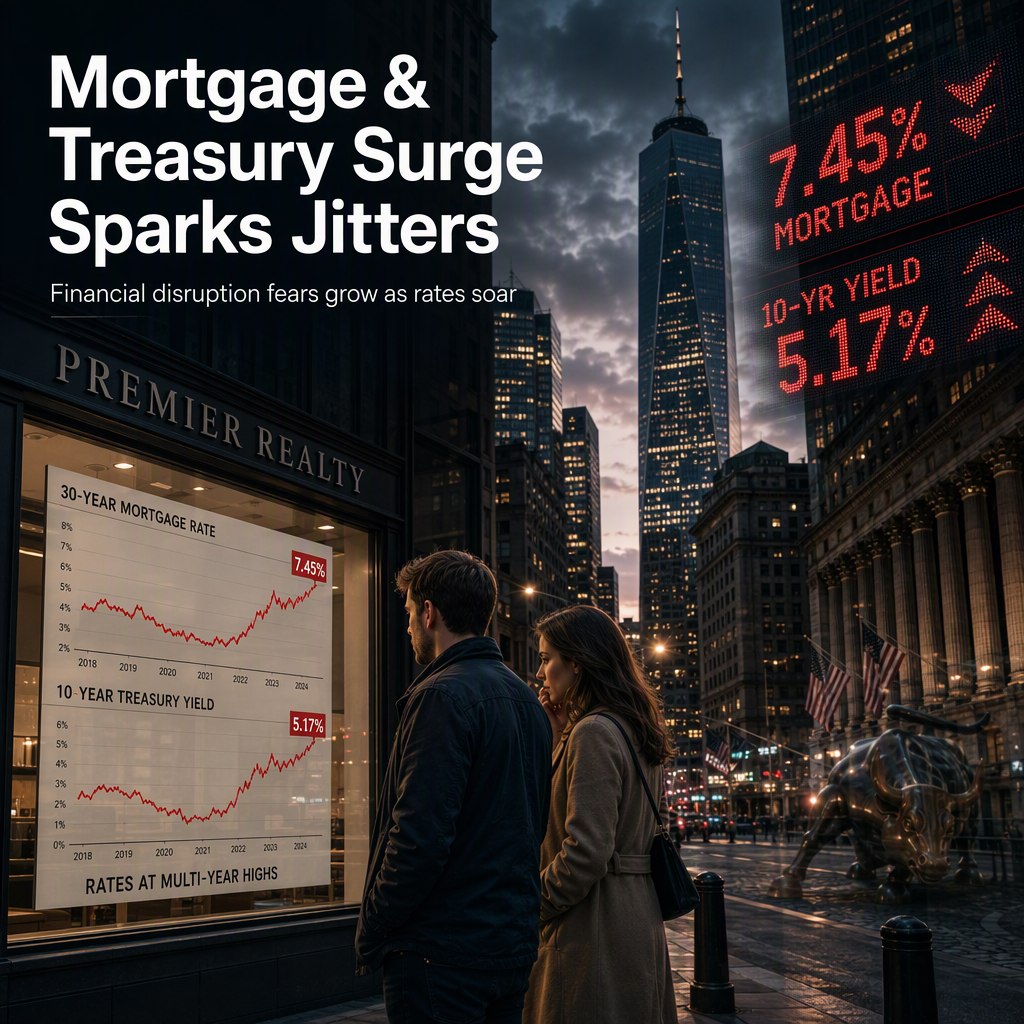
Mortgage rates in the United States have surged above 7% for the first time in more than two years, with the average 30-year fixed mortgage rate now at 7.45%, according to national surveys. This marks the highest level since mid-2024 and is making it increasingly difficult for Americans to enter the housing market or refinance existing loans [1]. The rise in mortgage rates is attributed to the Federal Reserve's ongoing efforts to combat inflation by increasing short-term interest rates, which has led to higher borrowing costs across the board [1]. For example, a 7.45% mortgage rate on a $400,000 home results in monthly payments that are several hundred dollars higher than at rates below 6% [1].
Simultaneously, the 10-year Treasury yield has experienced its most rapid one-day increase since April 2025, reaching 5.17% on Thursday, the highest level since July 2007 [2]. Two weeks prior, the yield was below 4.8%, and in August it was below 4.6% [2]. John Roque of 22V Research highlighted that in 16 instances since 1970 where the 10-year yield rose rapidly, a financial crisis followed each time [2]. Roque warned, "We should be prepared or forewarned that rates are rising and something is going to break" [2].
Market sentiment has turned cautious, with buyers waiting for rates to stabilize or drop before entering the housing market, and sellers facing fewer qualified buyers due to higher financing costs [1]. Technical analysis shows resistance at the 7.5% mortgage rate level, and analysts warn of a potential further slowdown in housing activity if rates continue to rise [1]. The rapid increase in the 10-year yield is particularly concerning to Wall Street observers, as it can disrupt financial markets and weigh on risk assets [2]. Roque noted that the 10-year Treasury yield serves as a benchmark for borrowing costs across the economy, and a swift rise can unravel risky financial positions [2].
Looking ahead, the Federal Reserve's next meeting and upcoming inflation data will be key indicators for the direction of mortgage rates [1]. Roque suggested that regional banks should be closely watched, as they may be particularly vulnerable in the current environment [2]. While the exact breaking point is not always clear in advance, historical precedent suggests that rapid increases in yields often lead to financial disruptions [2].
CONCLUSION
The sharp rise in both mortgage rates and Treasury yields is creating significant headwinds for the housing market and raising concerns about broader financial stability. Analysts and market participants are increasingly cautious, with historical patterns suggesting that such rapid rate increases often precede financial disruptions. The outlook remains uncertain, with future Federal Reserve actions and inflation data likely to determine the next moves in rates and market sentiment.