
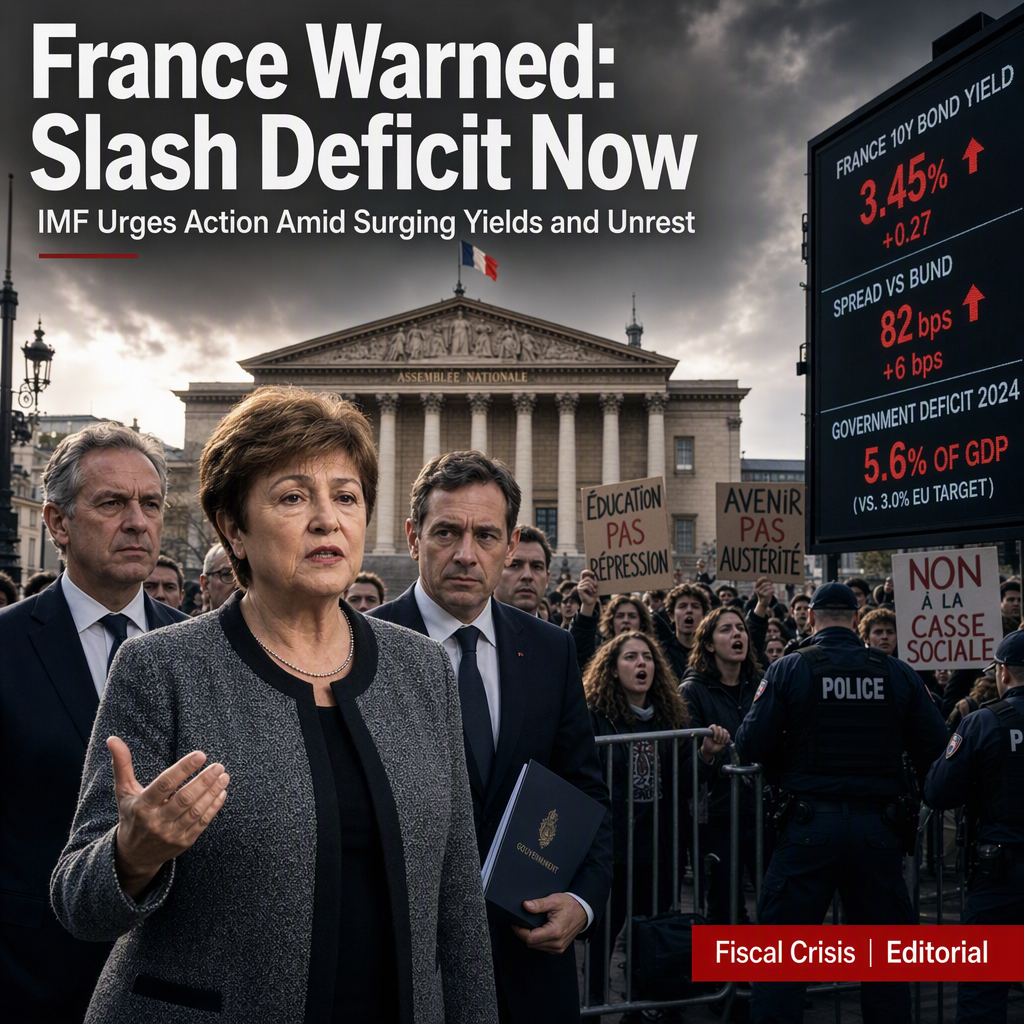
IMF Managing Director Kristalina Georgieva issued a stark warning to the French government, urging it to reduce its deficit in order to restore credibility with bond markets. This comes as France prepares for budget negotiations, aiming for a fiscal adjustment worth tens of billions of euros [1]. The country is currently experiencing a political crisis, with violent student protests entering their third week. These protests, driven by grievances over long study days, teacher shortages, and deteriorating school conditions, have added to the government's challenges in securing parliamentary support for significant spending cuts [1].
The political instability has directly impacted France's government bonds (OATs), with investors now demanding higher yields than for Italian government bonds. French 10-year bond yields have surged by more than 100 basis points since the start of the year [1]. Georgieva emphasized the need for France to bring its deficit under 5%, referencing the EU's excessive deficit procedure, which recommends a target closer to 3%. France's deficit reached 5.1% of GDP last year [1].
Despite the turmoil, Georgieva noted that Europe is better equipped to handle financial instability than during the euro zone sovereign debt crisis of the early 2000s, citing the strength of the European Central Bank and other protective instruments. However, she reiterated her message to France: "get your house in order" [1]. She acknowledged that implementing the proposed multi-billion-euro fiscal adjustment will be particularly challenging amid ongoing student protests [1].
CONCLUSION
France faces mounting pressure from the IMF to address its rising deficit as bond yields climb and political unrest intensifies. The combination of fiscal challenges and social instability has heightened market concerns, making the path to fiscal consolidation more difficult. The IMF's warning underscores the urgency for credible reforms to restore investor confidence.