
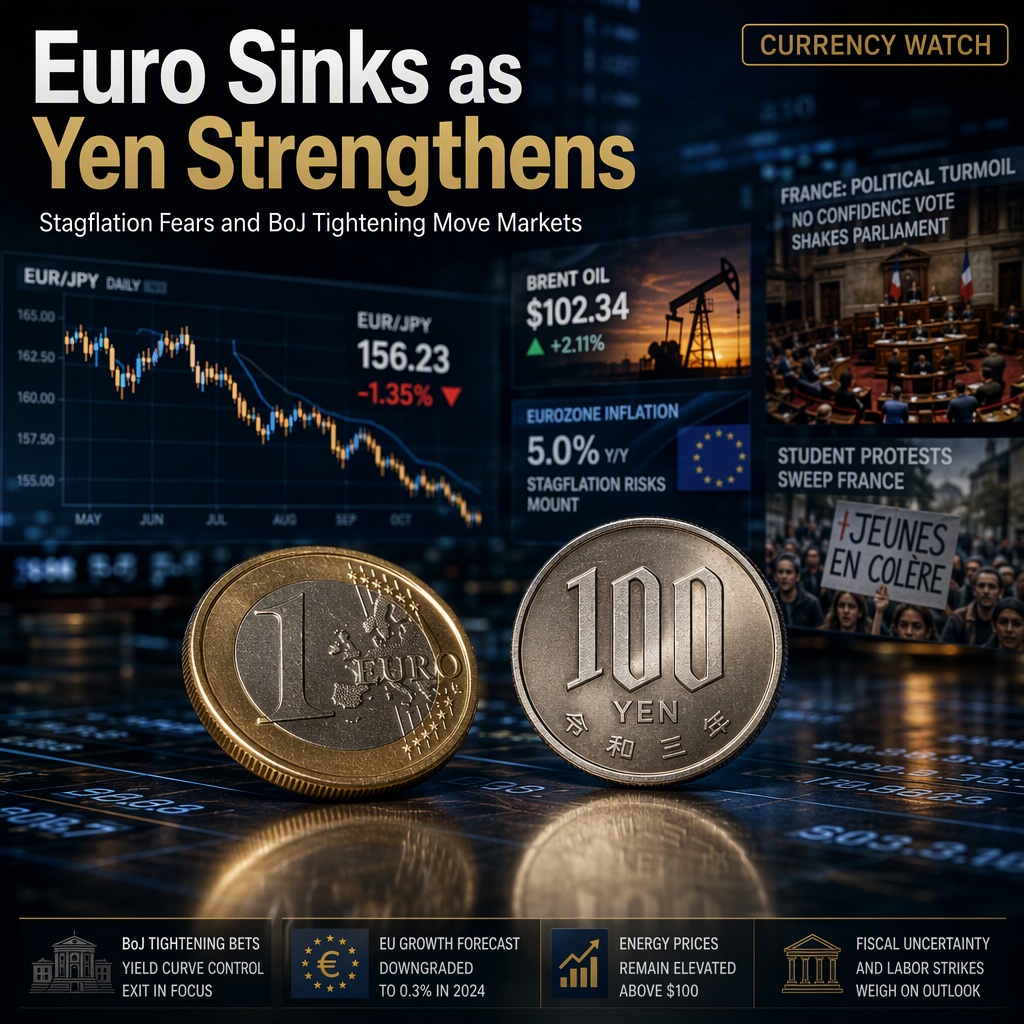
The Euro declined against the Japanese Yen, with EUR/JPY trading around 176.60 on Tuesday, down 0.21% on the day, as the Yen benefited from expectations of further monetary tightening by the Bank of Japan (BoJ) and the Euro faced pressure from political uncertainty in France and rising inflation concerns across the Eurozone [1]. On the European front, Germany's Harmonized Index of Consumer Prices (HICP) rose by 3.3% year-on-year in September, accelerating from 2.9% in August and 2.8% in July, and exceeding the 3% threshold for the first time since December 2023, primarily due to higher energy costs such as heating oil and motor fuels [1]. On a monthly basis, German consumer prices increased by 0.6%, compared with 0.2% previously [1]. Destatis President Ruth Brand highlighted the role of energy costs in driving inflation [1].
Elevated oil prices, with Brent Crude Oil remaining above $100 per barrel despite retreating from monthly highs above $105, have increased costs for European businesses and households, raising the risk of stagflation in the Eurozone as high energy prices combine with slowing economic activity [1]. This environment complicates the European Central Bank's (ECB) policy outlook, as policymakers must balance containing inflation with avoiding further economic weakness, potentially leading to a cautious monetary stance that could limit further Euro depreciation [1].
Political instability in France has further undermined confidence in the Euro, with rising government debt and challenges in securing parliamentary support for fiscal consolidation measures pushing French borrowing costs toward levels not seen since the European sovereign debt crisis [1]. Student protests demanding increased education funding have added to the uncertainty in France's political environment [1].
In Japan, the Yen has been supported by expectations of additional BoJ interest rate hikes and speculation about possible foreign exchange intervention by Japanese authorities [1]. Japan's Producer Price Index (PPI) increased by 6.8% year-on-year in September, indicating persistent inflationary pressures despite a slowdown from August, and reinforcing expectations of further monetary policy normalization by the BoJ [1].
Overall, EUR/JPY remains pressured between persistent inflation in Europe and expectations of tighter monetary policy in Japan, with market participants closely watching central bank actions and political developments for further direction [1].
CONCLUSION
The Euro's decline against the Yen reflects a combination of Eurozone stagflation risks, political instability in France, and expectations of BoJ tightening. Elevated energy prices and persistent inflation complicate the ECB's policy outlook, while the Yen is buoyed by prospects of further monetary normalization in Japan. Market sentiment remains cautious as traders monitor central bank moves and political developments.