
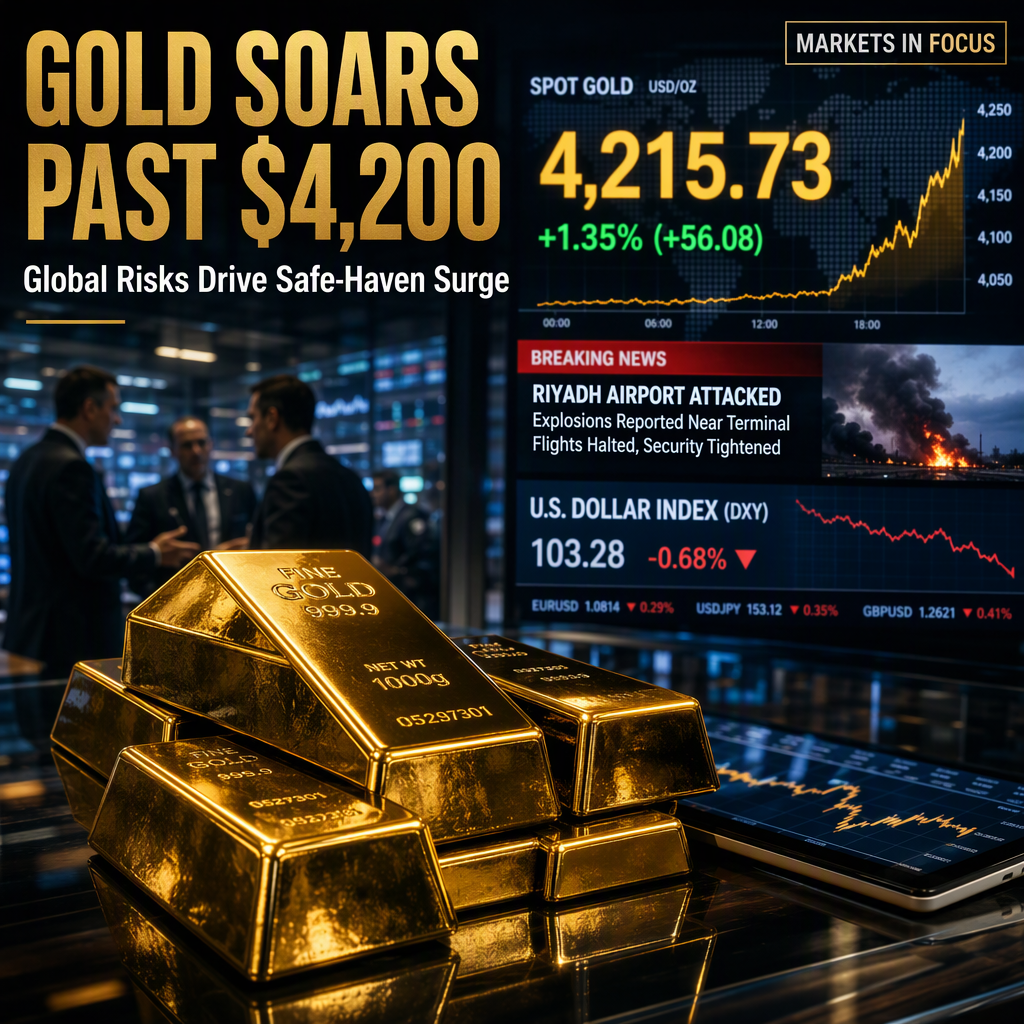
Gold prices climbed above $4,215 during the early Asian session on Monday, buoyed by surging inflows into gold-backed exchange-traded funds, which reached a four-year high according to Bloomberg data [3]. The People’s Bank of China added 740,000 ounces to its reserves in September, marking 23 consecutive months of gold purchases [3]. The rally in gold was further supported by a weaker US Dollar, as the US Dollar Index (DXY) drifted lower toward the 102.00 mark, pressured by softer US bond yields and a minor pullback from recent highs [2][3].
Geopolitical tensions in the Middle East escalated after a deadly Houthi attack on Riyadh’s King Khalid International Airport, prompting Saudi vows of retaliation and comments from President Donald Trump about potentially joining strikes on the group and resuming attacks on Iran [1][2][3]. These developments have heightened global inflation concerns due to their impact on oil prices, contributing to investor caution and increased demand for safe-haven assets like gold [1][3].
Market participants are closely watching upcoming US inflation data, with the Consumer Price Index (CPI) set for release on Wednesday and the Producer Price Index (PPI) and Retail Sales data on Thursday [1][2][3]. The CME FedWatch Tool indicates a 17.7% probability of a Federal Reserve rate hike in October, but an 84.1% chance of an increase in December [1][3]. Fed’s Musalem delivered a hawkish message, emphasizing the need for more monetary policy tightening due to persistent demand pressures and supply shocks, and highlighting structurally higher rates for longer [1][3]. Minutes from the September FOMC meeting confirmed that policymakers still view inflation as the dominant threat and support further policy tightening [2].
Analysts at TD Securities noted that trend-following funds are covering shorts across gold and platinum, with CTAs covering shorts by about 7% of historic max position size, suggesting a more supportive positioning for gold [3]. They cited geopolitical risk, fiscal concern, dollar debasement, de-dollarization, and stagflation concerns as major supportive factors for gold flows, and argued that the stage is being set for a potential new bull run into 2027 [3]. Meanwhile, the New Zealand Dollar (NZD/USD) remained subdued around 0.5610, pressured by the same geopolitical and inflationary concerns, with traders awaiting key domestic and US data releases later in the week [1].
CONCLUSION
Gold has rallied above $4,200, driven by strong ETF inflows, central bank buying, and heightened geopolitical risks, while the US Dollar and New Zealand Dollar face pressure from softer yields and inflation concerns. Markets are now focused on upcoming US inflation data and the Federal Reserve’s policy outlook, with a high probability of a rate hike in December. The combination of safe-haven demand and persistent inflation risks is keeping market volatility elevated.