
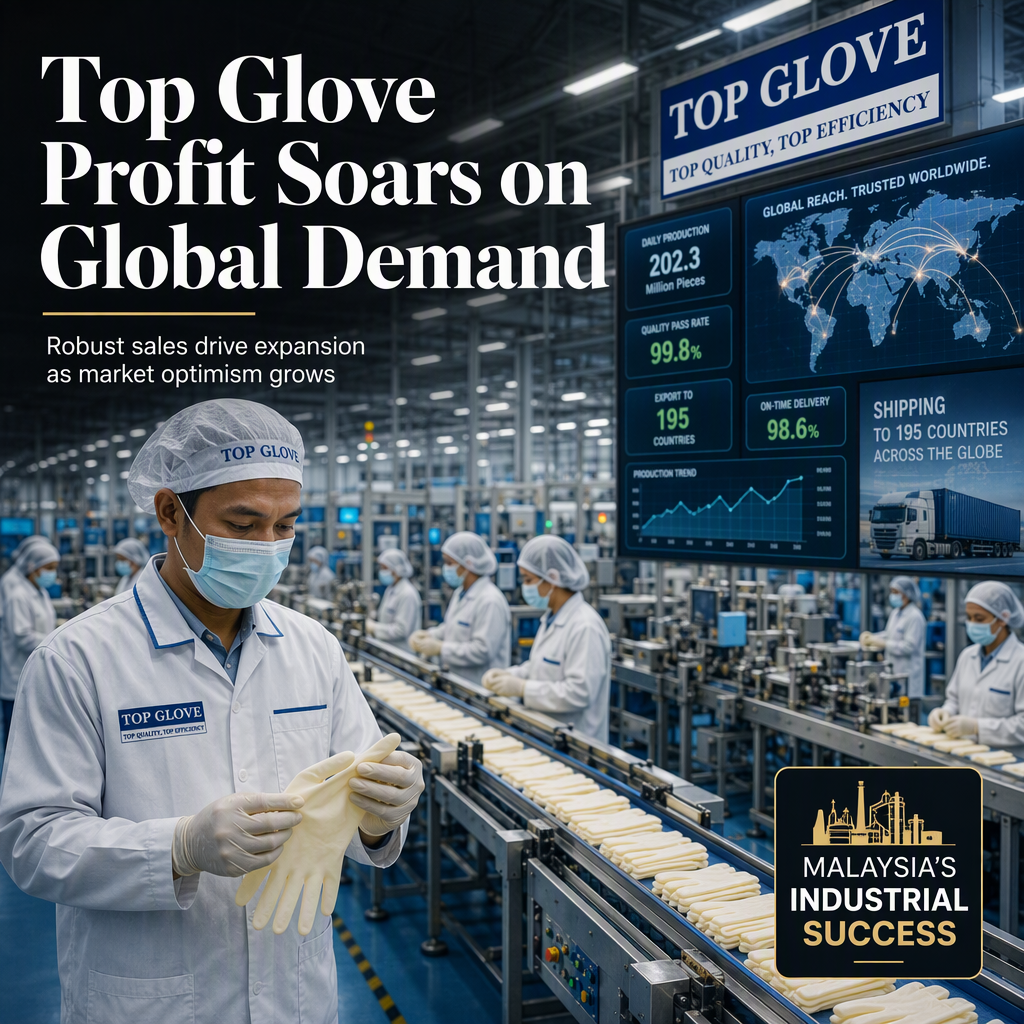
Malaysia's Top Glove, the world's largest rubber glove manufacturer, reported a near tripling of its annual net profit, attributing this significant financial performance to robust global demand for rubber gloves and the company's ability to pass rising material costs on to customers [1]. Despite facing high input prices, Top Glove maintained profitability by adjusting its pricing strategy, ensuring that increased costs did not erode its margins [1].
The company announced plans to further increase production capacity in response to sustained high demand, with management forecasting that global requirements for rubber gloves will exceed 400 billion units in 2026 [1]. A Top Glove factory in Shah Alam, Malaysia, was highlighted as part of the company's ongoing expansion efforts [1].
Financial analysts cited in the article view Top Glove's cost management and production expansion strategy as positioning the company favorably within the market. The expectation is that demand for rubber gloves will remain strong, driven by continued health awareness and needs in both medical and industrial sectors [1]. Market sentiment towards Top Glove is described as optimistic following the release of its strong earnings report, although no specific trading advice or technical indicators are provided [1].
CONCLUSION
Top Glove's ability to nearly triple its net profit despite high material costs underscores its strong market position and effective cost management. With plans to ramp up production and expectations of continued robust demand, the company's outlook remains positive, as reflected in the optimistic market sentiment following its earnings announcement.