
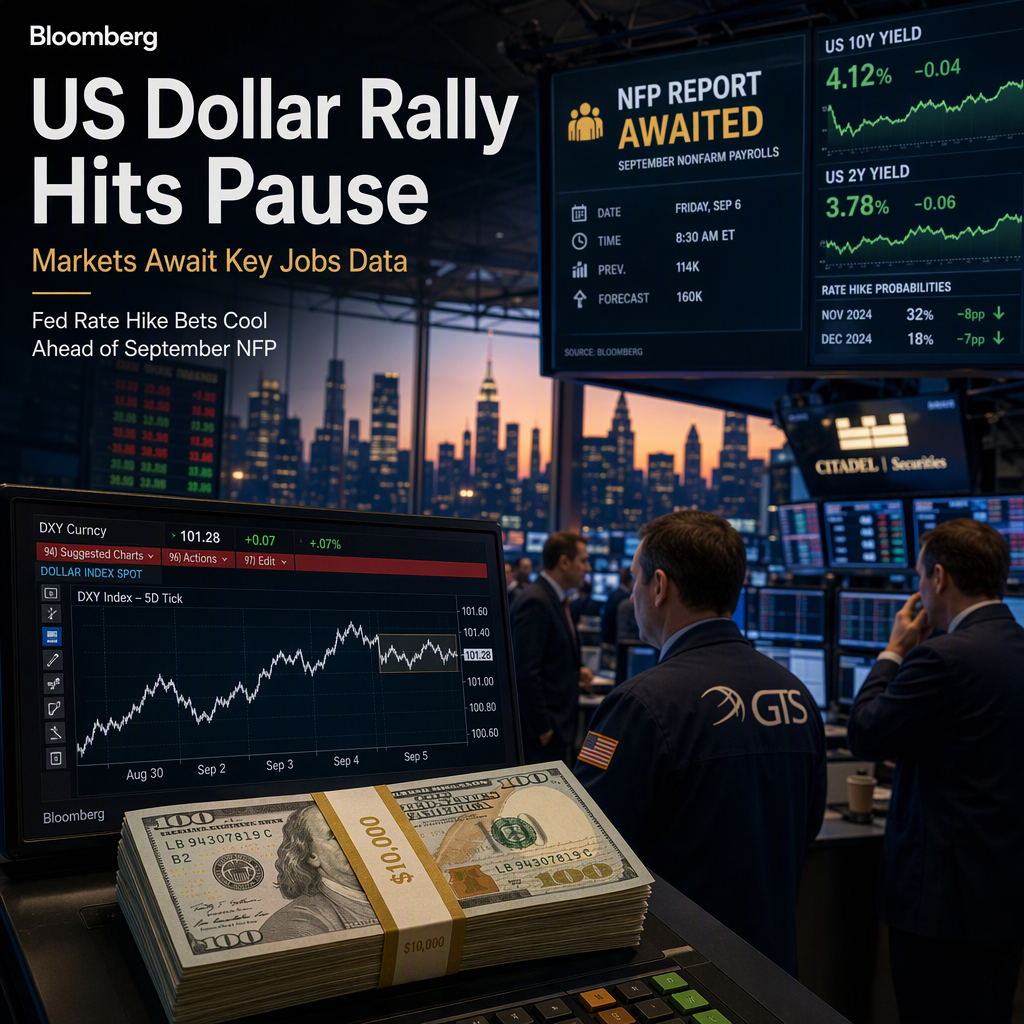
The US Dollar's recent rally and the concurrent bond market selloff have stalled, as comments from three key FOMC officials this week have reduced market expectations for a consecutive rate hike in October [1]. Despite this pause, the uptrend in the Dollar, which began after the strong August CPI print and was further boosted by the Federal Reserve's hawkish rate hike on September 16, remains intact. This ongoing strength is attributed to resilient US economic activity, robust labor demand, and persistent inflation, all of which continue to support the case for further Fed tightening [1].
The AtlantaFed GDPNow model currently estimates that annualized real GDP growth will reach 3.7% in Q3, up from 2.2% in Q2, highlighting the ongoing strength in the US economy [1]. Market participants are now focused on the upcoming September nonfarm payrolls (NFP) report, scheduled for release at 1:30pm London time (8:30am New York). The consensus forecast anticipates NFP gains of +90,000, compared to +162,000 in August. Bloomberg’s whisper number is slightly lower at +84,000, while alternative indicators such as ADP private payrolls and Revelio Labs employment data suggest even lower gains of +67,000 [1].
Fed Funds futures currently imply a total of 75 basis points of rate hikes over the next twelve months, reflecting ongoing expectations for further monetary tightening, albeit at a potentially slower pace than previously anticipated [1].
CONCLUSION
The US Dollar's uptrend remains supported by strong economic data and expectations of further Fed tightening, though the rally has paused as markets await the September NFP report. Market sentiment is cautiously optimistic, with attention focused on labor market data to gauge the likelihood of additional rate hikes.