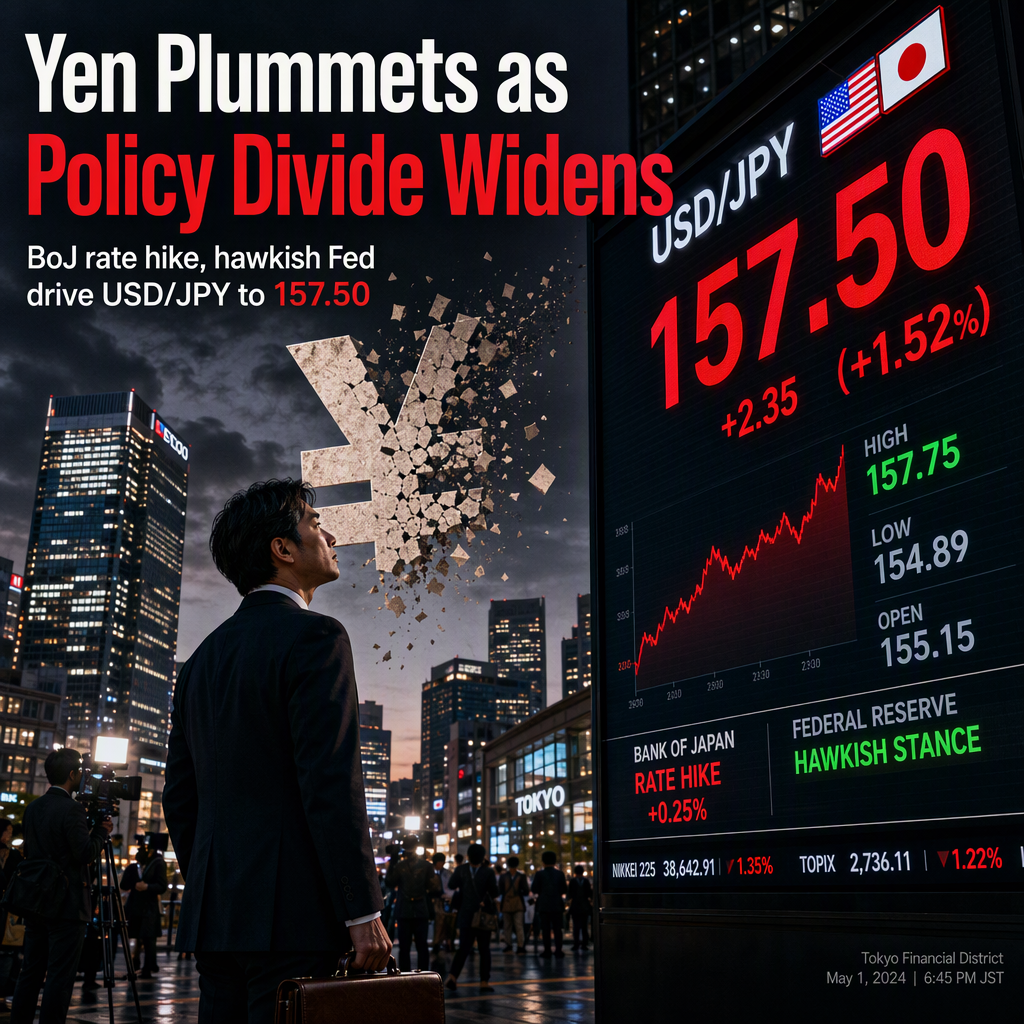
The Japanese Yen experienced significant volatility over the recent period, with the USD/JPY currency pair opening the week near 153.41 before a series of market events drove it sharply higher [1]. According to MUFG’s Teppei Ino, strong US Dollar buying ahead of both the Federal Open Market Committee (FOMC) and Bank of Japan (BoJ) meetings pushed the pair above 155 on September 14 [1]. The momentum stalled briefly around the 155 level, but following the FOMC meeting on September 16, which was perceived as hawkish and included a unanimous 25 basis point rate hike, the USD/JPY quickly advanced above 156 [1].
A temporary pullback occurred on September 17, with the pair falling below 155.50, attributed in part to lower crude oil prices [1]. However, the BoJ’s decision to raise its policy rate by 25 basis points, as widely expected, did not support the Yen. Instead, the Yen weakened further after it was revealed that two BoJ policy board members voted against the rate hike, leading to renewed selling and a surge in USD/JPY above 157 [1].
BoJ Governor Kazuo Ueda’s press conference initially sparked some Yen buying, but this move was short-lived. The Yen quickly resumed its decline, with the USD/JPY ultimately rising to above 157.50 [1]. Teppei Ino also notes that softer August Consumer Price Index (CPI) data contributed to the renewed Yen weakness against the Dollar [1].
The sequence of events highlights the market’s focus on central bank policy divergence and the sensitivity of the Yen to both domestic and international monetary policy signals. The combination of a hawkish FOMC, a divided BoJ rate hike, and softer inflation data in Japan all contributed to the Yen’s sharp depreciation [1].
CONCLUSION
The Japanese Yen weakened significantly as a result of a hawkish FOMC, a divided BoJ rate hike, and softer inflation data. Market participants responded by pushing USD/JPY to new highs above 157.50, underscoring the impact of central bank policy divergence on currency markets.