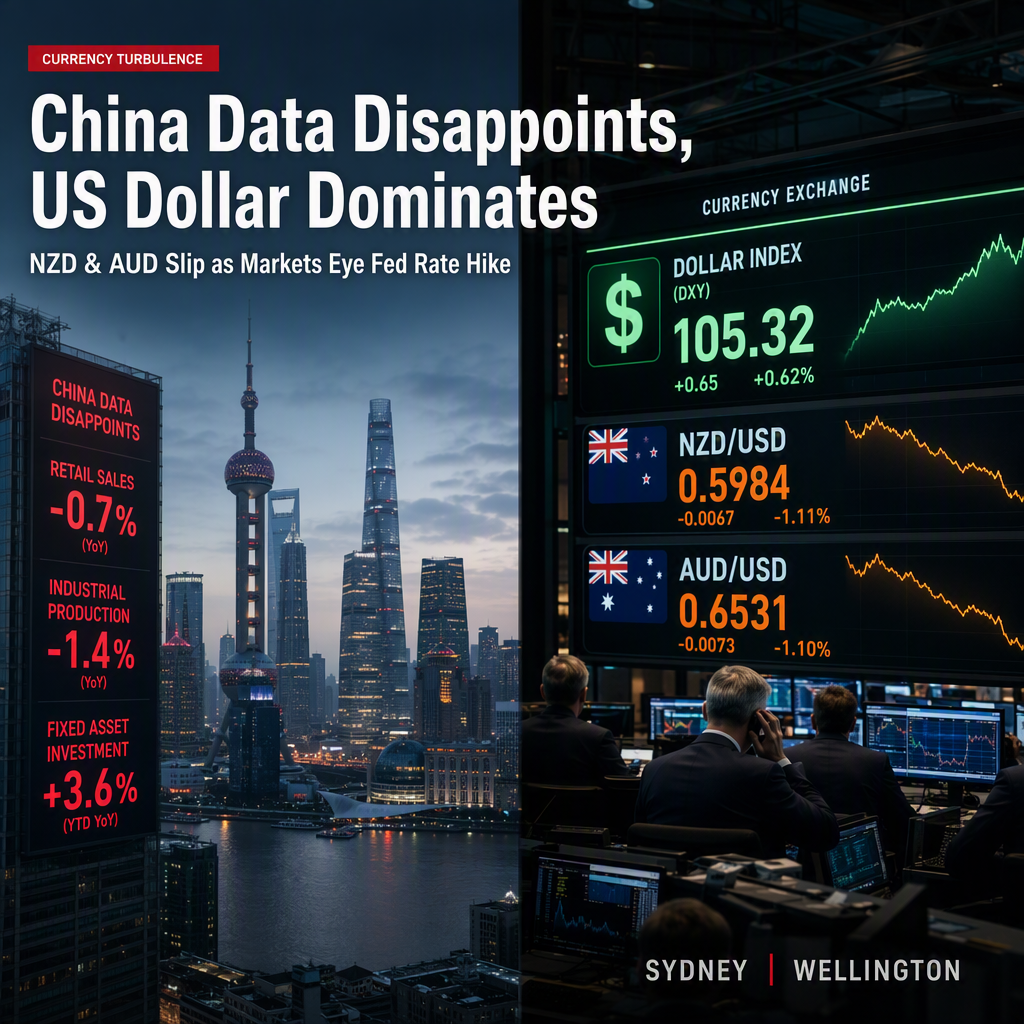
China released key economic data for August, revealing that Retail Sales rose by 0.4% year-over-year, falling short of the expected 0.8% increase and lower than the 0.6% growth recorded in July [1][2][3]. Industrial Production, however, climbed 5.2% YoY, surpassing both the 4.8% forecast and the previous month's 4.5% [1][2][3]. Fixed Asset Investment came in at -7.2% year-to-date YoY, matching expectations but marking a further decline from July's -6.7% [1][2][3].
The release of this mixed Chinese data had a subdued impact on both the New Zealand Dollar (NZD) and the Australian Dollar (AUD), currencies closely tied to China's economic performance due to strong trade links. The NZD/USD pair extended its losses for a second consecutive day, trading around 0.5760 during Asian hours on Tuesday [1]. Similarly, the AUD/USD pair remained depressed near the 0.7130 region, trading with a negative bias for the second straight day and showing little reaction to the Chinese data [2][3]. At the time of reporting, AUD/USD was down 0.10% on the day at 0.7132 [3].
Market sentiment was dominated by a stronger US Dollar, buoyed by rising expectations of a US Federal Reserve interest rate hike this week. Money markets reflected over a 92% chance of a rate hike, a significant jump from about 60% a week earlier, according to CME FedWatch data [1]. This expectation, combined with rising energy costs and inflation concerns, pushed the US 10-year Treasury yield toward 5% [1]. The robust US Dollar acted as a headwind for both NZD and AUD, overshadowing any potential impact from the Chinese data [1][2][3].
Technical analysis for AUD/USD indicated that the pair was pressing just under the 23.6% Fibonacci retracement at 0.7147, with the 50-day Simple Moving Average at 0.7074 providing near-term support [2]. Despite the negative bias, expectations that the Reserve Bank of Australia (RBA) might raise interest rates later this month could help limit further losses for the AUD/USD pair [2].
According to the sources, the mixed Chinese data failed to provide meaningful impetus to the China-proxy currencies, with broader market moves driven by US monetary policy expectations and global risk sentiment [2][3].
CONCLUSION
China's latest economic data showed weaker-than-expected retail sales but stronger industrial production, resulting in little positive momentum for the New Zealand and Australian Dollars. Instead, both currencies remained under pressure from a strengthening US Dollar amid heightened expectations of a US Federal Reserve rate hike. The market's focus remains on US monetary policy, with Chinese data having a muted effect on currency movements.