
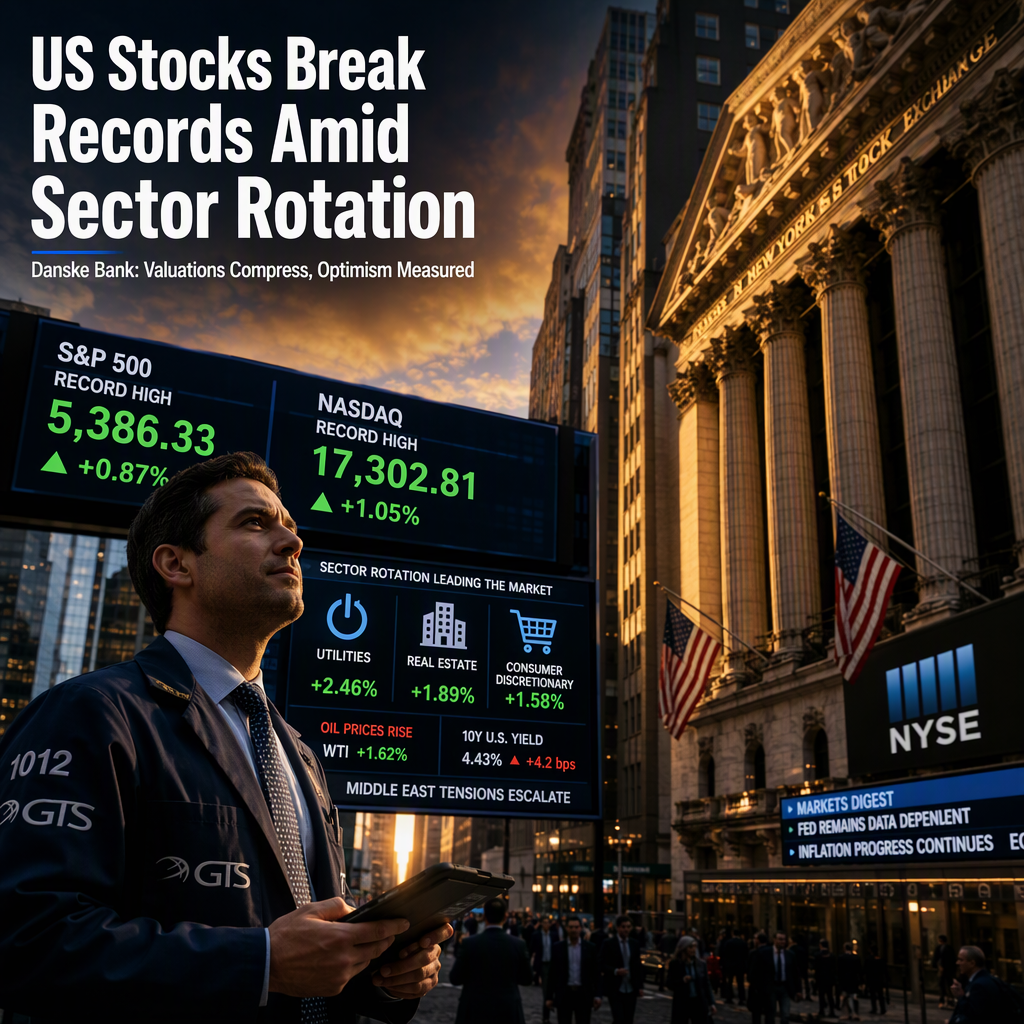
According to the Danske Research Team, US equities extended their rebound with both the S&P 500 and Nasdaq reaching fresh record highs, gaining 0.5-0.6% respectively in the latest session [1]. The rally was characterized as a relief rally, with some of the weakest-performing sectors in recent months—utilities, real estate, and consumer discretionary—leading the market higher, each rising between 1% and 3% on the day [1].
The Danske Research Team emphasized that these new all-time highs occurred despite ongoing challenges such as renewed escalation in the Middle East, persistently high oil prices, rising bond yields, and increasingly tightening central banks [1]. They highlighted that the S&P 500 has already shed roughly a fifth off its valuation multiple over the past year, and has become 5% cheaper over the last quarter, even after the recent rebound [1].
Danske Bank disagrees with the view that equity markets are excessively optimistic, arguing that markets have priced the current earnings backdrop fairly conservatively throughout the year [1]. The team noted that while equities, credit markets, and bonds have reacted differently in recent weeks, this divergence reflects the distinct factors driving each asset class [1].
For equities, the dominant driver remains future nominal earnings growth, with the energy shock and higher rates impacting certain sectors more than others. However, as long as returns on investment continue to grow faster than the discount rate, earnings will remain the key determinant of broad equity performance, according to Danske Bank [1].
CONCLUSION
US equities have reached new record highs, supported by compressed valuation multiples and sector rotation into recent laggards. Danske Bank maintains that the market's optimism is not excessive, with future earnings growth remaining the primary driver of equity performance. Despite macroeconomic headwinds, the outlook for equities remains constructive as long as earnings growth outpaces discount rates.